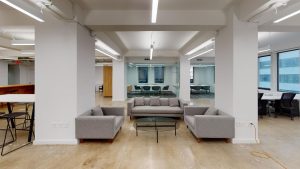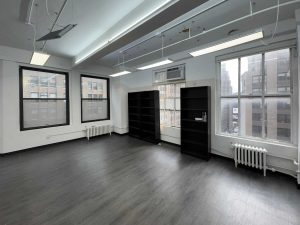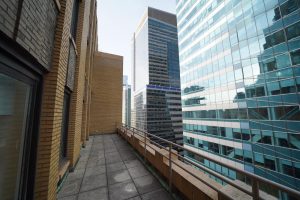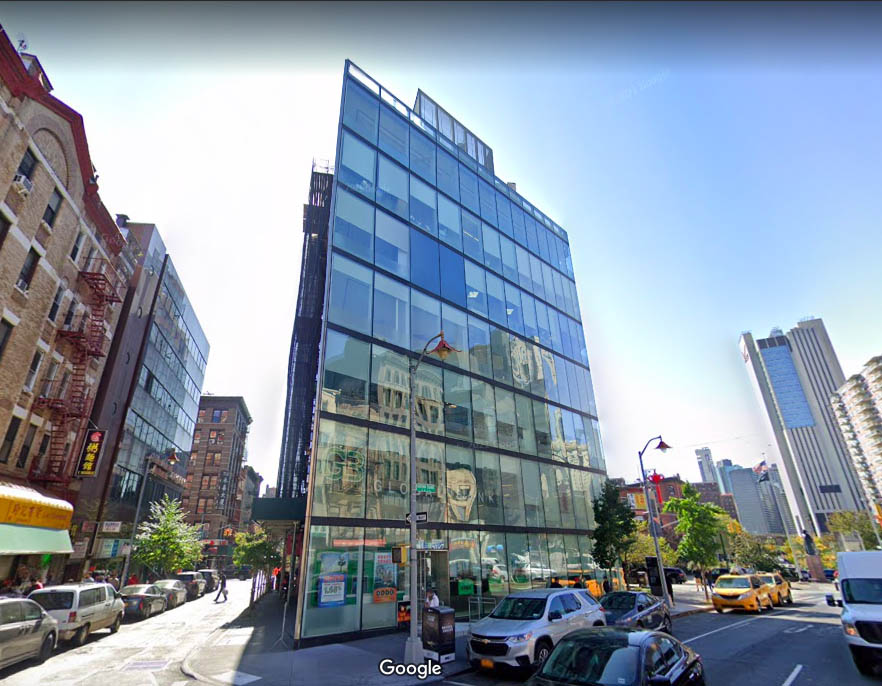


Two blocks south of the courthouses and one bridge ramp from Brooklyn, Lower Manhattan runs out of expens...
Learn more about Chinatown


Downtown covers about 90 million SF of office space across five very different submarkets: the Financial District, the World Trade Center and World Financial Center complex, Civic Center, City Hall / Insurance, and Chinatown. They don’t price the same, they don’t lease at the same pace, and they don’t attract the same tenants. Where you land Downtown matters as much as whether you land Downtown.
If you’re looking at Downtown right now, you’re looking at a market that keeps tightening. Cushman & Wakefield’s third-quarter numbers put Downtown vacancy at 21.0%, its lowest in 20 quarters, and Class A asking rents at $65.96/SF, the highest since mid-2020. CBRE has the average asking rent up 8% in a year, to $62.40/SF, which works out to about $23,000 more a year on a 5,000 SF office than the same space asked a year ago.
What that means for you: the days of naming your price Downtown are ending. Sublease space, the old shortcut to a cheap deal, fell 22.8% in the quarter to 2.7M SF, the least since early 2020, per Cushman & Wakefield. If you’ve been waiting for landlords to get more desperate, they’re getting less desperate. There’s still about 17M SF of vacant space across the district, which is plenty of room to find what you need, but the leverage isn’t what it was last year.
Many of our clients are teams of 5 to 30 people, not Aon renewing 202,000 SF at One Liberty Plaza. The big Downtown deals get the headlines, but the older towers in the Financial District and around City Hall lease suites from under 1,000 SF to about 6,000 SF, and many come prebuilt.
Plan on about 150 to 250 square feet per person, depending on how many private offices you want. That works out to roughly 750 to 1,250 square feet for 5 people, 2,250 to 3,750 for 15, and 4,500 to 7,500 for 30. Our office space calculator will give you a closer number before you tour.
Downtown is the cheapest of Manhattan’s three main office markets. Cushman & Wakefield’s third-quarter Downtown average was $58.09/SF, and suites we listed in older buildings in December and January asked less, about $40 to $55/SF. At $48/SF, a 2,500 SF office for about 12 people costs about $10,000 a month before electricity.
Ask about prebuilt suites. Landlords build them out ahead of time with offices, a conference room, and a kitchen, so you can sign and move in within weeks instead of waiting months for construction.
Where small teams should look:
For two to five people, a private office in a coworking space can cost less than a lease of your own. Our coworking page covers the options nearby.
| Submarket | Asking Rent (Direct) | Profile | Best For |
| Financial District | Class A $60 to $75/SF | Class B and A, large floor plates | Financial services, law, professional services |
| WTC / World Financial | Premium Class A / Trophy | Trophy Class A | Media, finance, tech, AmEx HQ (2031) |
| Civic Center | Class A $55 to $65/SF | Mostly Class B | Government, law, advocacy, nonprofits |
| City Hall / Insurance | Class A $55 to $65/SF | Class B and C | Insurance, government-adjacent, professional |
| Chinatown | Class B and C value tier | Class B and C | Small business, retail, healthcare, value tenants |
This year has been a real turning point. Cushman & Wakefield counts 4.5M SF of new leasing Downtown through September, up 63.2% from a year earlier and the most for the first nine months since 2019. CBRE, which counts differently, has 2.66M SF, down 16% on the year. The firms disagree on the pace, but both show Downtown tightening: C&W has vacancy at a 20-quarter low, and CBRE has availability down 3.9 points in a year. Downtown is being chosen again.
The headline event was American Express committing to nearly 2 million SF at 2 World Trade Center. The announcement landed February 25, 2026, and it’s the kind of deal that resets how landlords think about asking rents on the rest of the campus. Silverstein Properties is developing the 55-story Foster + Partners tower on Port Authority land. Construction started on July 9, 2026. Amex stays at 200 Vesey Street until the building opens in 2031. Cushman & Wakefield represented Amex, JLL and Savills advised the Port Authority, and CBRE represented Silverstein. Why this matters to you: when an anchor of that size commits Downtown, every WTC-area landlord knows they’re not the next concession-heavy deal. Pricing power has shifted.
For broader context, see our recent post on the largest Manhattan office leases of 2025.
The Downtown price range is wide, and the spread is your friend if you know how to use it. A small business in Chinatown can land Class C space for a fraction of what a hedge fund pays for trophy floors at the top of the WTC towers. Cushman & Wakefield put Downtown’s Class A asking rent at $65.96/SF in the third quarter, up $2.37 from the second, but that average hides everything that actually matters: which submarket, which building, which floor.
And Class B is where the conversation gets interesting. Cushman & Wakefield’s April report put the Class A premium over Class B Downtown at 25.5% in Q1 2026, up from 14% in mid-2024, the widest gap in two years at the time, and Class A took 87.0% of Downtown’s new leasing through September. If your team needs a Class A address for client meetings or recruiting, that gap costs you. If you can make Class B work, that gap is leverage. Same building, same neighborhood, same subway, often the same lobby renovation, and you walk in with a lot more room to negotiate. Not sure how much space you actually need? Run your headcount through our Office Space Calculator before you tour anything.
| Submarket | Class A $/SF | Class B / C Coverage | Availability | Typical Lease Size | Tier |
|---|---|---|---|---|---|
| Financial District | $60 to $75 | Class B and Class C inventory available; see C&W gap commentary above | ~17 to 19% | 2,500 to 50,000+ SF | Class B / Mixed |
| WTC / World Financial | Premium / Trophy | Limited Class B; no Class C | ~12 to 15% | 10,000 to 200,000+ SF | Trophy |
| Civic Center | $55 to $65 | Mostly Class B with some Class C | ~16 to 19% | 2,000 to 25,000 SF | Mostly Class B |
| City Hall / Insurance | $55 to $65 | Class B and Class C inventory available | ~16 to 19% | 1,500 to 20,000 SF | Class B and C |
| Chinatown | Limited | Class B and Class C dominate | ~18 to 22% | 1,000 to 8,000 SF | Value |
| Downtown Average | $65.96 (C&W, Q3 2026) | 25.5% Class A premium over Class B (C&W, Q1 2026) | 15.9% (CBRE, Q3 2026) | Varies | Mixed |
Downtown Class A average asking rent ($65.96/SF) from Cushman & Wakefield, Manhattan Office MarketBeat Q3 2026, which also publishes Class A averages for six Downtown submarkets: $57.03/SF in Financial East, $68.52/SF in Financial West, $53.89/SF in City Hall, $63.96/SF in Insurance, $81.25/SF in World Trade, and $89.19/SF in TriBeCa. Downtown availability (15.9%) from CBRE, Manhattan Downtown Office Figures Q3 2026 (October 7, 2026). The 25.5% Class A premium over Class B is Cushman & Wakefield's Q1 2026 figure (April 2026); no firm has published a Q3 update. Submarket-level Class A bands, availability ranges, and typical lease sizes are Metro Manhattan internal research (May 2026), and the brokerages' submarket boundaries don't match ours exactly. Asking rents, before concessions.
Class A clusters in two places Downtown: around the WTC campus and along Water Street, with another pocket in the Financial District core. Cushman & Wakefield put the Downtown Class A average at $65.96/SF in the third quarter and its World Trade submarket at $81.25/SF, but if you’re looking at trophy floors at the top of the World Trade Center towers, expect to pay meaningfully more (Metro Manhattan internal research, May 2026). Those views, those amenities, those addresses don’t come at the district average.
The Amex deal at 2 World Trade Center gave every other landlord around the WTC a fresh data point on what their building is worth. If you’re looking at trophy Class A Downtown, your timeline matters. Anchors like 28 Liberty Street, One Liberty Plaza, and 85 Broad Street have always commanded premium pricing, but the trajectory now is upward, not flat. For a deeper look at what actually sets trophy buildings apart from regular Class A, see our piece on how trophy buildings set themselves apart in NYC.
Most of the leasable space Downtown is Class B. Think buildings in the 100,000 to 800,000 SF range with renovated lobbies, modern mechanical systems, and a short walk to whatever subway line gets your people to work. If you’re a midsize firm that doesn’t need a trophy address to win business, this is probably where you should be looking.
The gap between Class A and Class B is widening. In April, Cushman & Wakefield put the Class A premium over Class B Downtown at 25.5% for Q1 2026, up from 14% in mid-2024 and the widest gap in two years. No firm’s third-quarter report publishes a Downtown Class B rent, but the direction hasn’t changed: C&W’s Class A average rose another $2.37 in the third quarter alone, to $65.96/SF.
Why is that gap so wide? Because demand has tilted hard toward Class A. C&W says Class A took 87.0% of Downtown’s new leasing through September (Q3 2026), after taking 73% of all Downtown leasing from 2020 through early this year (April 2026). Class B and lower-tier assets have seen demand soften, marketing periods stretch out, and tour activity drop (Cushman & Wakefield, April 2026). Translation: Class B landlords are more motivated than they’ve been in a long time. If you can make Class B work, you can probably make a really good deal.
Buildings worth knowing on the Class B side: 100 Wall Street, 80 Broad Street, 110 Wall Street, 39 Broadway, and a deep pool of Water Street stock. Most carry active capital-improvement programs and offer prebuilt, move-in-ready suites for smaller tenants. If you’re not sure what “Class B” actually means in 2026 or how it compares to Class A and Class C, our explainer on Class A, B, and C buildings breaks it down.
If your priority is keeping your fixed costs as low as possible and you don’t need to impress anyone with your lobby, Class C is where the deals live. Most of it is older walk-ups, small elevator buildings, or 5 to 12-story properties that haven’t been renovated in a while. The approved brokerages don’t publish a Class C average for Downtown, so anyone giving you a single number is making it up.
The deepest Class C inventory Downtown is in Chinatown and the older blocks of the Financial District. Pricing typically sits well below Class B, but how far below depends entirely on the building, the floor, and the block (Metro Manhattan internal research, May 2026). This is a tier where touring matters way more than averages.
What you actually get for Class C money: attended or buzzer-entry lobbies, tenant-controlled HVAC, and basic shared amenities. It’s the right call for small businesses, early-stage startups, medical and dental practices, nonprofits, and anyone who’d rather put the budget into people and product than into a marquee address.
This is the part most tenants under-negotiate. The asking rent is the headline. The free rent and TI allowance is where the real value lives, especially Downtown and especially outside the trophy tier. The ranges below are typical-market figures from Metro Manhattan internal research (May 2026), based on our recent deals. What you actually get on your lease depends on your credit, your term, the building, and how the negotiation runs. For a benchmark, CBRE says new Downtown leases over 25,000 SF have averaged 17 months of free rent and $142/SF in improvement allowances since 2023, against 12 months in 2019, and those averages lean toward big deals. On a 5,000 SF office at $58/SF, each free month is worth about $24,000. (Not sure whether a 3-year, 5-year, or 10-year term fits you? That’s a real decision worth thinking through before you sit down with a landlord.)
| Tier | Free Rent | TI Allowance | Notes |
|---|---|---|---|
| Trophy and premium Class A | 8 to 12 months | $90 to $140/SF | The narrowest concessions Downtown, because the landlord knows the next tenant is right behind you. |
| Standard Class A | 12 to 16 months | $70 to $110/SF | This tier gets you a quality address and generous concessions without trophy pricing. |
| Class B | 14 to 18 months | $60 to $90/SF | Spec suites widely available. If you can take a 10-year term, this tier has the most room to negotiate. |
| Class C | 12 to 18 months | $35 to $65/SF | Many landlords will hand you a fully built-out turnkey suite so you can sign and move in the same month. |
Concession ranges are typical-market figures from Metro Manhattan internal research (May 2026), based on recent deals. Benchmark: CBRE says new Downtown leases over 25,000 SF have averaged 17 months of free rent and $142/SF in improvement allowances since 2023, against 12 months in 2019, and those averages lean toward big deals.
On a Class B Downtown deal, your net effective rent usually lands well below the face rent your broker first quotes you. It takes a few minutes to learn, and it’s often worth more than anything you win on the asking rent. Our deeper look at rising landlord concessions walks through how it works.
Downtown stopped being a finance-only neighborhood a long time ago. Media, tech, fashion, advertising, government, and law all have meaningful footprints here, and each of them gravitates to different blocks for different reasons. Use the table below to find your business type, see where you’d fit, and see what kind of building you’d be touring.
| Industry | Best-Fit Submarkets | Class Fit | Example Buildings |
|---|---|---|---|
| Banking / Financial Services | WTC, Financial District | Class A / Trophy | One World Trade Center, 4 World Trade Center, 100 Wall Street, 85 Broad Street |
| Media / Publishing | WTC | Class A / Trophy | Conde Nast at One WTC, 3 World Trade Center, 4 World Trade Center |
| Technology / SaaS / AI | WTC, Financial District | Class A | Spotify at 4 WTC, Brookfield Place, One Liberty Plaza |
| Big Law / International Law Firms | Financial District, WTC | Class A / Trophy | 28 Liberty Street, One Liberty Plaza, 1 World Trade Center |
| Mid-Market Law / Boutique | Financial District, Civic Center | Class A / Class B | 65 Broadway, 100 Wall Street, 80 Broad Street, 26 Broadway |
| Government / Public Sector | Civic Center, City Hall / Insurance | Class A / Class B | 100 Church Street, 49-51 Chambers Street, 26 Broadway |
| Insurance / Reinsurance | City Hall / Insurance, Financial District | Class A / Class B | 100 Maiden Lane, 80 Pine Street, 14 Wall Street |
| Consumer Products / Fashion / Advertising | Financial District, WTC | Class A | 3 World Trade Center, 195 Broadway, 4 World Trade Center |
| Nonprofits / Advocacy | Civic Center, City Hall / Insurance | Class B | 65 Broadway, 50 Broadway, 26 Broadway, 39 Broadway |
| Medical / Dental Practices | Financial District, Chinatown | Class B / Class C | 65 Broadway, 100 Church Street, side-street buildings in Chinatown |
| Startups / Small Business (<20 ppl) | Chinatown, Financial District side streets | Class B / Class C | 39 Broadway, 100 Wall Street, 80 Maiden Lane, Chinatown loft inventory |
| Retail / Showroom | WTC retail concourse, Broadway storefronts | Variable | Westfield WTC, Brookfield Place, Broadway storefront retail |
Industry fit and example buildings: Metro Manhattan internal research.
If you toured Downtown ten years ago, you’d find a totally different market. The WTC campus, Brookfield Place, and a long run of capital improvements at older Financial District and Water Street buildings have changed what tenants get when they sign here. Amenities aren’t a perk anymore. They’re how landlords compete for your business, and how you’ll compete to attract people back to the office. Three tiers of amenity packages are common Downtown:
Trophy and World Trade Center tier: Tenant-only amenity floors with conferencing, lounges, fitness, and dining. Concierge services, observation decks (One World Observatory), and direct PATH and subway access. LEED certification across most WTC buildings (Gold or Platinum). When 2 World Trade Center opens, it adds more than an acre of landscaped terraces and gardens to the campus.
Class A and renovated Class B core: Renovated lobbies, on-site fitness, conferencing facilities, modern mechanical systems, ground-floor retail and dining, and walking-distance transit. Many Financial District Class A buildings added tenant-only amenity floors during the 2018 to 2024 capital-improvement cycle.
Class B and Class C: Pre-war character, attended or buzzer-entry lobbies, tenant-controlled HVAC, and increasingly common spec suites with furniture and IT cabling preinstalled.
See all Downtown buildings or filter active listings by size and price.
For background on landlord ownership in NYC, see our overview of the biggest commercial real estate landlords in NYC.
| Landlord | Notable Downtown Properties | Approx. Downtown Portfolio | Typical Lease Profile |
|---|---|---|---|
| Silverstein Properties | 1, 3, 4, and 7 World Trade Center; 2 World Trade Center (in development) | ~10M SF (WTC complex) | 20,000+ SF |
| Brookfield Properties | Brookfield Place, One Liberty Plaza, 225 Liberty Street, 250 Vesey Street | ~12M SF | 15,000+ SF |
| Port Authority of New York and New Jersey | Land owner of WTC complex (long-term ground leases) | Ground lessor | Ground lease |
| Rudin Management | 55 Broad Street, 80 Pine Street, 110 Wall Street, 32 Avenue of the Americas | ~6M SF Downtown | 5,000+ SF |
| SL Green Realty | 180 Maiden Lane, 1 Madison Avenue (Midtown South), selective Downtown holdings | ~3M SF Downtown | 10,000+ SF |
| Fosun International | 28 Liberty Street | ~2.2M SF (single asset) | 10,000+ SF |
| Vornado Realty Trust | Selective Downtown holdings | ~2M SF Downtown | 15,000+ SF |
| The Witkoff Group | Selective Downtown holdings, primarily mixed-use and conversion plays | ~1M SF | 10,000+ SF |
| GFP Real Estate | 39 Broadway, 25 Broadway, 1 Battery Park Plaza, multiple older Downtown assets | ~5M SF | 2,000+ SF |
| Time Equities | 111 John Street, 125 Maiden Lane, multiple older Downtown buildings | ~3M SF | 2,000+ SF |
| Cove Property Group | 100 Wall Street | ~510,000 SF (single asset) | 5,000+ SF |
| Beacon Capital Partners | 85 Broad Street | ~1.1M SF (single asset) | 10,000+ SF |
Portfolio figures are approximate and limited to Downtown holdings. Several landlords listed also operate significant inventory in Midtown, Midtown South, and outside Manhattan.
One Downtown selling point you can use with your team: it’s one of the most transit-rich office submarkets in the country. Whether your people are coming from Brooklyn, Queens, New Jersey, or even Staten Island, they can probably get to the Fulton Street complex or the World Trade Center Transportation Hub (Oculus) without a transfer. If commute time is hurting retention right now, Downtown deserves a serious look. Run specific addresses through our Commute Calculator to see what your people would actually experience.
| From | To Downtown (Fulton or WTC) | Mode |
|---|---|---|
| Hoboken, NJ | 10 to 15 min | PATH to WTC |
| Jersey City (Exchange Place) | 5 to 10 min | PATH to WTC |
| Newark, NJ | 20 to 25 min | PATH to WTC |
| Williamsburg, Brooklyn | 20 to 28 min | J or M to Fulton |
| Downtown Brooklyn | 8 to 15 min | 2, 3, 4, 5, or R to Fulton |
| Park Slope, Brooklyn | 20 to 28 min | R to Whitehall or 4/5 transfer |
| Long Island City, Queens | 20 to 28 min | 7 to Times Sq + 2/3 to Fulton |
| Astoria, Queens | 30 to 40 min | N or W to Whitehall |
| Stamford, CT | 65 to 75 min | Metro-North to Grand Central + 4/5 |
| Hicksville, NY (Long Island) | 55 to 65 min | LIRR to Penn + 2/3 to Fulton |
| Midtown (Grand Central) | 15 to 20 min | 4 or 5 to Fulton |
Cushman & Wakefield’s third-quarter numbers put Downtown’s average asking rent at $58.09/SF, up $1.43 from the second quarter, with Class A at $65.96/SF. CBRE, which counts only fully modernized buildings, had $62.40/SF, up 8% from a year earlier. Among C&W’s Downtown submarkets, averages ran from about $50/SF in City Hall and Financial West to $73.01/SF in World Trade and $87.28/SF in TriBeCa. Chinatown, which neither firm tracks separately, sits at the bottom of the range (Metro Manhattan internal research, May 2026).
Cushman & Wakefield put Downtown Class A asking rents at $65.96/SF in the third quarter of 2026, up $2.37 from the second quarter and the highest since mid-2020. Savills had Downtown Class A at $71.46/SF. C&W’s World Trade submarket averaged $81.25/SF for Class A, and trophy floors at the top of the WTC towers run higher still (Metro Manhattan internal research, May 2026). Class A inventory clusters around the World Trade Center campus and along Water Street.
The third-quarter reports we checked from Cushman & Wakefield, CBRE, and Savills don’t publish a Downtown Class B average. The newest comparison is Cushman & Wakefield’s April 2026 report, which found a 25.5% Class A premium over Class B Downtown in Q1 2026, up from 14% in mid-2024. Class C inventory typically prices below Class B, with the exact delta depending on the building and location (Metro Manhattan internal research, May 2026). Many Class B and C landlords offer fully built-out spec suites with furniture and IT cabling included.
Chinatown is the most affordable Downtown submarket, with inventory concentrated in Class B and Class C buildings (Metro Manhattan internal research, May 2026). The big brokerages don’t track it separately. Among the submarkets they do track, Cushman & Wakefield’s third-quarter averages were lowest in Financial West ($49.98/SF) and City Hall ($50.00/SF), and CBRE’s City Hall district averaged $54.28/SF. Civic Center and City Hall / Insurance also offer Class B value for small businesses, medical practices, nonprofits, government-adjacent tenants, and startups.
Among the five submarkets on this page, the World Trade Center area commands the highest rents, with Cushman & Wakefield’s third-quarter numbers putting its World Trade submarket at $73.01/SF overall and $81.25/SF for Class A. C&W also counts TriBeCa as Downtown, and its $87.28/SF average is higher still. We cover Tribeca on our Hudson Square and Tribeca page. Construction of American Express’s 55-story headquarters at 2 World Trade Center began July 9, 2026, and it’s scheduled to open in 2031.
CBRE put Downtown availability at 15.9% in the third quarter of 2026, down 0.7 percentage points from the second quarter and 3.9 points from a year earlier. Cushman & Wakefield tracks vacancy, a different measure, and had it at 21.0%, a 20-quarter low after a 1.3-point drop. C&W also counted 2.7M SF of sublease space, down 22.8% in the quarter and the lowest since Q1 2020. Each firm counts a different set of buildings, so compare a firm’s numbers over time rather than across firms.
American Express’s commitment to nearly 2 million SF at 2 World Trade Center, announced February 25, 2026, is still the biggest Downtown deal in years. The 55-story tower broke ground on July 9, and completion is scheduled for 2031. The largest Downtown deals named in the third-quarter reports were renewals: Aon’s 202,000 SF at One Liberty Plaza (Cushman & Wakefield) and Seward & Kissel’s 171,112 SF at 1 Battery Park Plaza (CBRE). The biggest new leases on CBRE’s list were Morgan & Morgan’s 70,602 SF at 199 Water Street and Amwins’ 45,559 SF at One Liberty Plaza.
Small businesses (under 5,000 SF) typically find the best Downtown value in Class B and Class C buildings across the Financial District core, Chinatown, and Civic Center. Common destinations for this tenant size include 39 Broadway, 65 Broadway, 100 Wall Street, 80 Maiden Lane, and Chinatown loft inventory (Metro Manhattan internal research, May 2026). Many landlords offer fully built-out spec suites with flexible 3 to 5 year terms.
Downtown is served by 13 subway lines (1, 2, 3, 4, 5, 6, A, C, E, J, R, W, and Z) plus PATH service to New Jersey through the WTC Transportation Hub. The Fulton Street complex is the largest Downtown subway hub. The Staten Island Ferry runs from Whitehall Terminal, and NYC Ferry runs from Pier 11 Wall Street.
Brookfield Properties is the largest Downtown landlord, with roughly 12M SF of holdings including Brookfield Place, One Liberty Plaza, and 225 Liberty Street. Silverstein Properties controls the World Trade Center complex (1, 3, 4, and 7 WTC, plus 2 WTC in development), totaling about 10M SF. Other major Downtown landlords include Rudin Management, SL Green Realty, Fosun International (28 Liberty), GFP Real Estate, and Time Equities.

Two blocks south of the courthouses and one bridge ramp from Brooklyn, Lower Manhattan runs out of expens...
Learn more about Chinatown
City Hall office space is the last real bargain in Lower Manhattan, and most tenants walk right past it o...
Learn more about City Hall/Insurance
Civic Center office space is what you lease when your business lives and dies by the courts and City Hall...
Learn more about Civic Center
The Financial District is the oldest office market in New York and known as the home to Wall Street, the ...
Learn more about Financial District
The trophy towers here ask the highest rents in Lower Manhattan. The World Trade Center and World Financi...
Learn more about WTC/World FinancialAccessibility Tools