
How to Negotiate Office Space Leases in New York City
Let’s say you’re a business owner in the heart of New York City.


Most people pick Grand Central for one reason: the commute. Then they sign a lease and discover everything else. This is the most connected patch of office space in the country, the place where Metro-North, the Long Island Rail Road, four subway lines, and a supertall full of hedge funds all stack on top of the same train hall. If half your team rides in from Connecticut, Westchester, or Long Island, the search basically starts and ends here.
But the headline rent hides a lot. Grand Central is really two markets under one name. Up top, One Vanderbilt still commands the highest rents around the terminal, including a $345/SF lease JLL reported in the third quarter. Down in the older Class B and C towers along Third and Lexington, landlords are still dealing, though Cushman & Wakefield’s submarket vacancy has fallen to 16.6%. The submarket overall asking rent is $76.83/SF, with Class A at $85.34/SF (Cushman & Wakefield, Q3 2026). On a 3,000 SF office, the gap between those two averages is about $25,500 a year, and the blended number hides a spread bigger than almost anywhere in Midtown. Where you land in these few blocks matters far more than the fact that you landed here.
Many of our clients are teams of 5 to 30 people, not firms taking four floors at 245 Park or paying $345/SF at One Vanderbilt. The record rents get the headlines, but plenty of buildings within a few blocks of the terminal lease suites of about 2,000 to 7,500 SF, and many of those come prebuilt.
Plan on about 150 to 250 square feet per person, depending on how many private offices you want. That works out to roughly 750 to 1,250 square feet for 5 people, 2,250 to 3,750 for 15, and 4,500 to 7,500 for 30. Our office space calculator will give you a closer number before you tour.
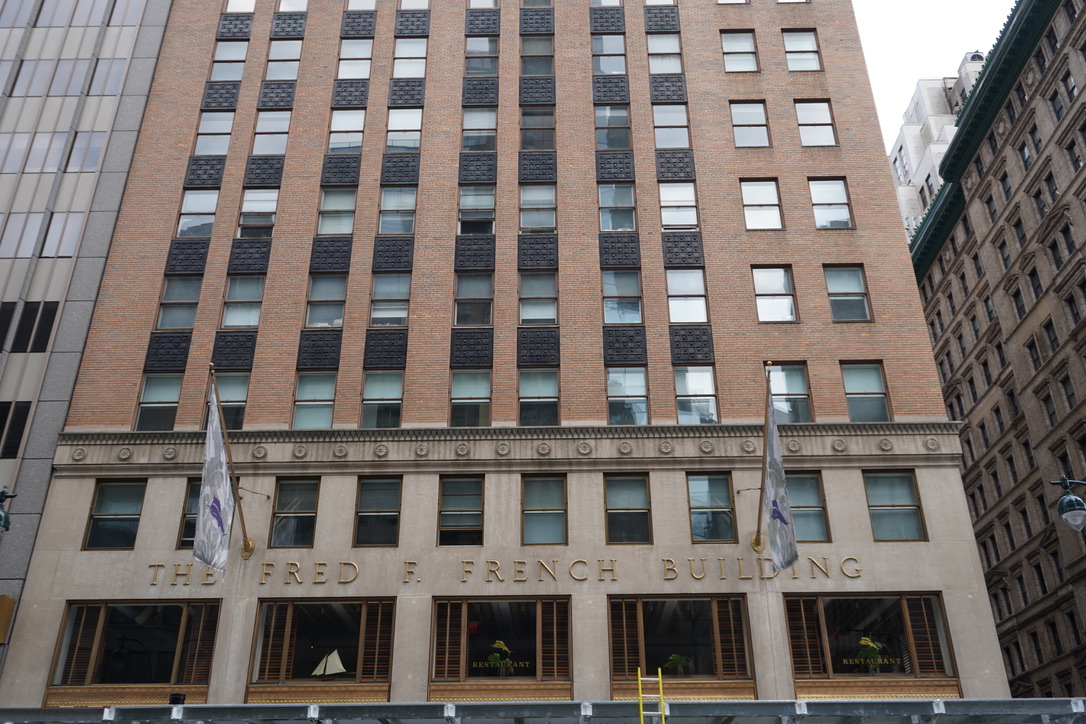
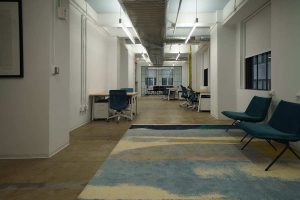
The older buildings near the terminal are where small teams get the most for their money. Suites listed on our site this year at 315 Madison Avenue, the Chanin Building and 6 East 45th Street asked about $49 to $66/SF, and Durst quoted $80/SF on a full-floor deal at 5 Grand Central East in August. At $60/SF, a 2,000 SF office for about ten people costs about $10,000 a month before electricity.
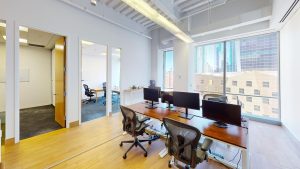
Ask about prebuilt suites. Landlords build them out ahead of time with offices, a conference room, and a kitchen, so you can sign and move in within weeks instead of waiting months for construction. Empire State Realty Trust has a 2,948 SF prebuilt suite available at One Grand Central Place, and the Chanin Building’s newly built 29th-floor corner suite has five private offices, a conference room and a pantry.
Buildings to start with:
For two to five people, a private office in a coworking space can cost less than a lease of your own. Our coworking page covers the options near the terminal.
| Sub-Area | Profile | Best For | Tier |
|---|---|---|---|
| Vanderbilt trophy core | One Vanderbilt and the new supertall product wrapping the terminal | Hedge funds, banking, AI flagships, Big Law | Trophy |
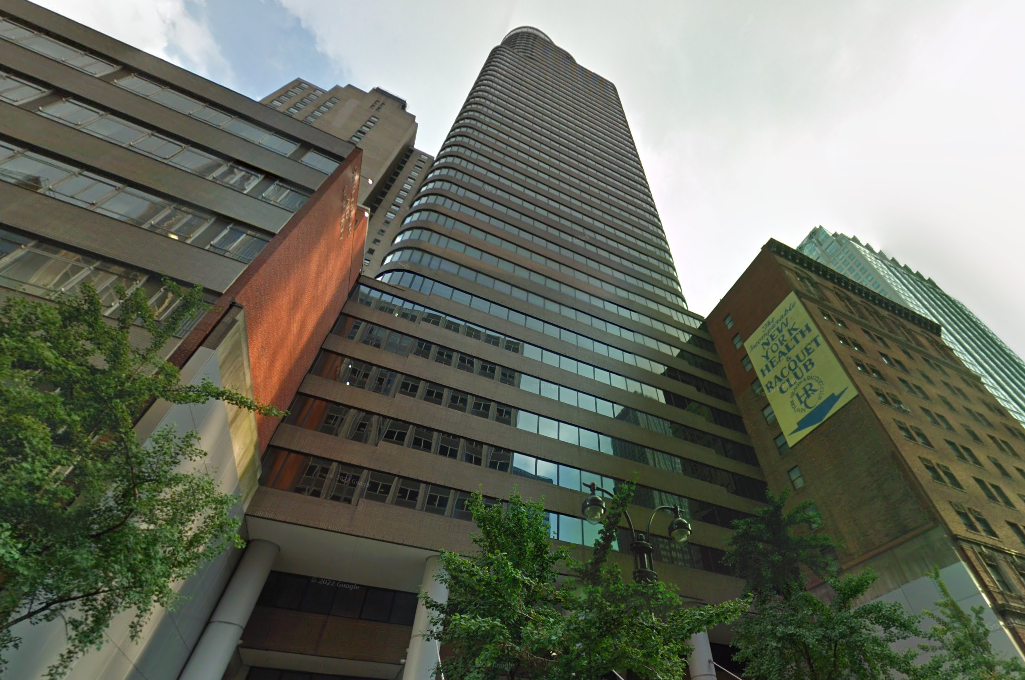
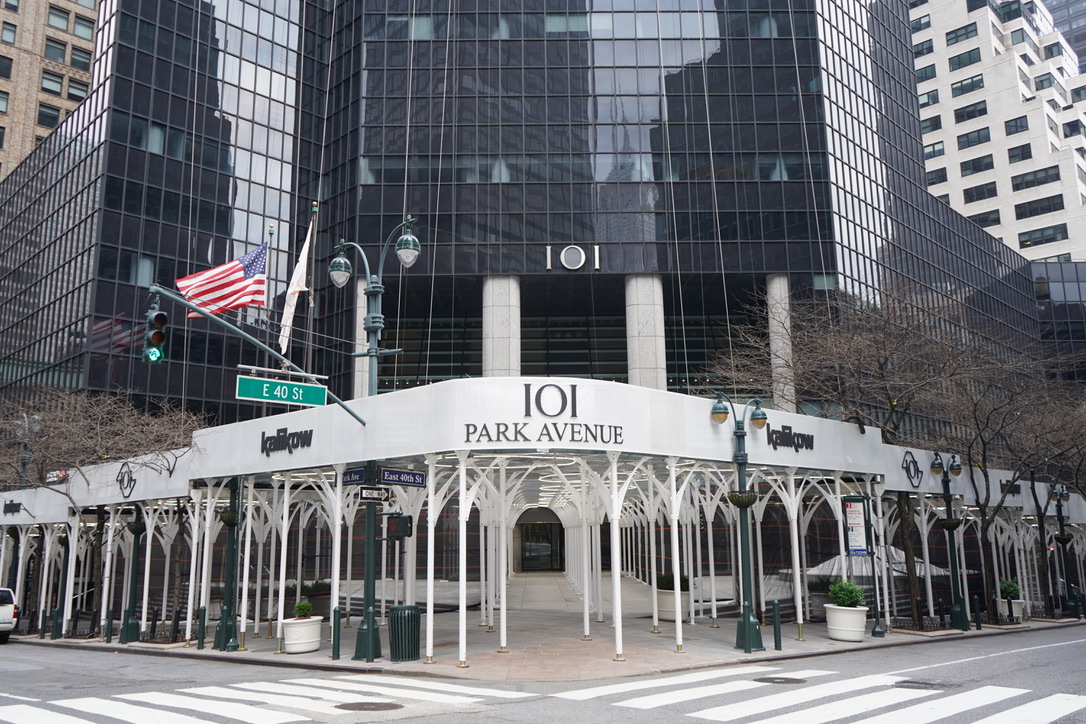
| Park Avenue frontage | Grand prewar and renovated towers ringing the terminal (200, 230, 245 Park; 90/100/101 Park) | Finance, asset management, law, corporate HQs | Trophy / Class A |
| 42nd Street spine | Landmark Class A and B towers facing the terminal along 42nd Street | Law, finance, commuter HQs, professional services | Class A / B |
| Madison side streets | Boutique and midsize Class A/B buildings just west of the terminal | Boutique finance, law, creative, professional services | Class A / B |
| Lexington & Third value | Older Class B and C stock east of the terminal | Startups, medical, small business, back office | Value |
Most tenants shop Grand Central as if it were one market. It’s really two: a trophy market and a value market that share a train station. A deal at One Vanderbilt has nothing to do with a deal in a 1960s tower on Third Avenue, and if you don’t figure out which one you’re shopping, you’ll lose a month touring buildings that were never going to work.
The wider backdrop is strong. Manhattan just had its strongest first nine months of leasing since 2000, 32.86 million SF, and availability fell to 12.4% in the third quarter, the tenth straight quarter of tightening or holding steady (Colliers, Q3 2026, via Commercial Observer, October 2026). Midtown’s overall asking rent was $78.83/SF, with Class A at $90.57/SF, the highest since 2008 (Cushman & Wakefield, Q3 2026), and CBRE put Midtown availability at 12.1%, its lowest since early 2020 (CBRE, Q3 2026). Grand Central is moving with that tide, just at two very different speeds depending on the block.
It depends on which side of the terminal you’re standing on. The submarket overall asking rent was $76.83/SF in the third quarter, with Class A at $85.34/SF (Cushman & Wakefield, Q3 2026). But that blended figure is close to meaningless on its own, because Grand Central runs from $345/SF at One Vanderbilt down to value office space in the $50s along Third Avenue. Savills, using a different inventory mix, pegs the submarket higher at $87.57/SF, and CBRE’s Grand Central district sits at $78.29/SF (both Q3 2026). All three numbers are real. They’re just counting different buildings.
Start with the question that matters most for your budget: do you need a trophy address? If hedge-fund LPs or Am Law 100 clients walk through your lobby every week, yes. For most everyone else, no. The bulk of Grand Central’s leasable space is Class B and older Class A in the towers ringing the terminal, and it prices well below the trophy line for the same five-minute walk to your train. Not sure how much space you need? Run your headcount through our Office Space Calculator before you tour anything.
| Sub-Area | Class A Profile | Class B / C Coverage | Availability | Typical SF for New Leases | Tier |
|---|---|---|---|---|---|
| Vanderbilt trophy core | Trophy supertall (One Vanderbilt) | None | ~0 to 5% | 7,000 to 100,000+ SF | Trophy |
| Park Avenue frontage | Premium Class A / trophy | Limited Class B | ~7 to 12% | 10,000 to 50,000+ SF | Trophy / A |
| 42nd Street spine | Class A core | Class B available | ~14 to 18% | 2,500 to 40,000 SF | Class A / B |
| Madison side streets | Class A / boutique | Class B available | ~14 to 18% | 2,000 to 20,000 SF | Class A / B |
| Lexington & Third value | Limited Class A | Class B and C dominate | ~18 to 24% | 1,500 to 25,000 SF | Value |
| Grand Central average | $85.34 Class A | $76.83 overall asking | 16.6% vacancy | Varies | Mixed |
Grand Central overall asking rent of $76.83/SF, Class A asking rent of $85.34/SF, and 16.6% vacancy from Cushman & Wakefield, Manhattan Office MarketBeat Q3 2026. For the Park Avenue frontage, CBRE put its Park Avenue district at $112.90/SF with 6.2% availability in Q3 2026, and Cushman & Wakefield's Park Avenue submarket averaged $132.25/SF with 10.3% vacancy, the lowest of the 20 Manhattan submarkets it tracks. Sub-area profiles, coverage descriptors, and availability ranges are Metro Manhattan internal research (May 2026); approved firms publish the Grand Central submarket figures but do not publish breakouts by sub-area. Vacancy and availability are different measures: vacancy counts empty space, availability counts space being marketed, including occupied space offered for sublease.
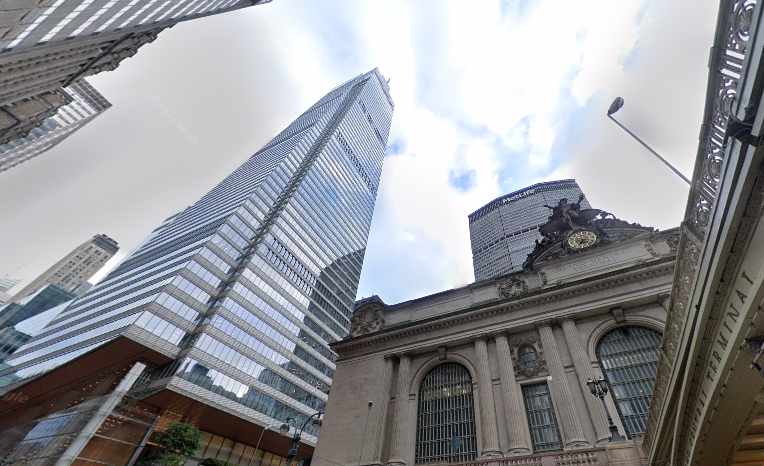
Trophy in Grand Central means one building above all others: One Vanderbilt. SL Green’s 1,401-foot, 1.6M SF supertall sits directly on top of the terminal, opened in 2020, and has been effectively fully leased since the end of 2025. It’s the building that reset the market: Nscale signed at $320/SF in the first quarter (JLL via Commercial Observer, April 2026), JLL’s third-quarter research reported Sentinel at $345/SF, and a 73rd-floor sublease was asking $350/SF in the spring. Tenants include TD Bank and TD Securities, the Carlyle Group, and McDermott Will & Emery. It has a 30,000 SF amenity floor, Michelin-starred dining from Daniel Boulud, the Summit observation deck, and a private entrance straight into Grand Central. See the One Vanderbilt profile.
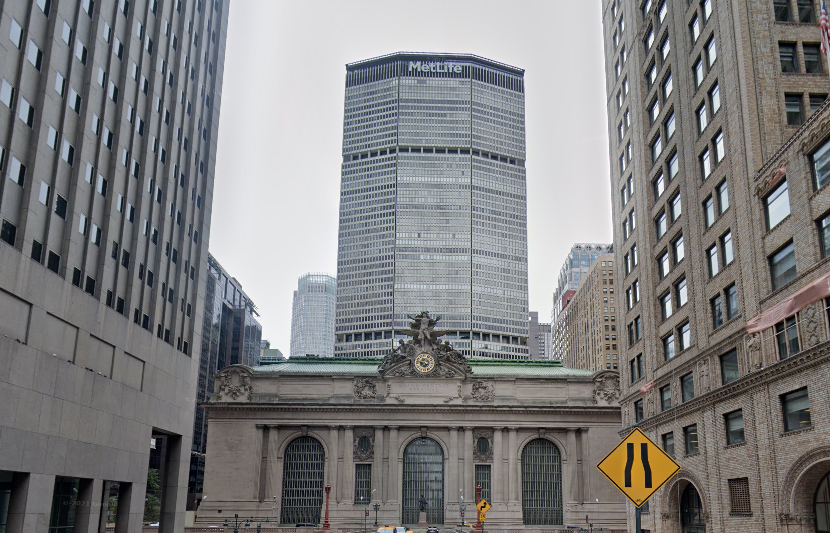
The rest of the trophy and premium Class A space is on the Park Avenue blocks around the terminal: 200 Park (the MetLife Building), 230 Park (the Helmsley Building), and 245 Park, with 90, 100, and 101 Park a block or two south. CBRE put its Park Avenue district at $112.90/SF in the third quarter with just 6.2% availability, and Cushman & Wakefield’s Park Avenue submarket has the lowest vacancy of the 20 it tracks in Manhattan, at 10.3% (Q3 2026). Supply is shrinking and prices are climbing. If you really need a trophy address on these blocks, move now or wait for 175 Park Avenue, which is still years from opening. For what actually separates trophy from regular Class A, see our piece on how trophy buildings set themselves apart in NYC, and our rundown of the top 10 Class A buildings in Midtown.
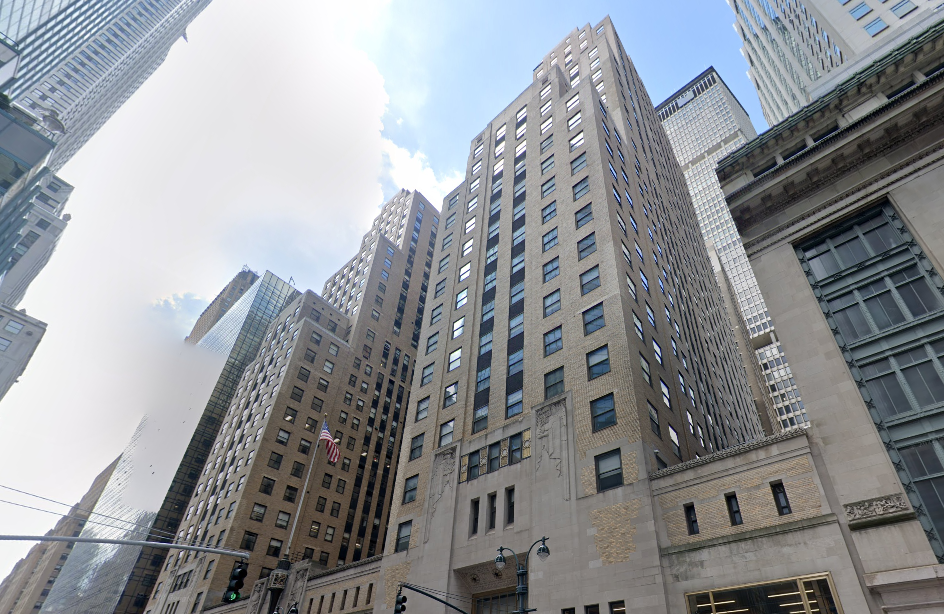
This is where most Grand Central leases get signed. If you’re a midsize firm that’s growing steadily and doesn’t need to impress a hedge fund every Tuesday, this is your tier, and there’s plenty of inventory. The good Class B sits along 42nd Street and the Madison side streets, in older buildings most people would still call beautiful, like the Chanin Building. A lot of these landlords spent real money on lobbies and prebuilt spec suites over the last five years, so a 2026 Class B floor here often shows like a 2018 Class A. That’s a big upgrade for your team without a big jump in rent.
On pricing, the submarket overall asking rent was $76.83/SF in the third quarter (Cushman & Wakefield, Q3 2026), and Class B typically prices below that. How far below depends entirely on the building and the block (Metro Manhattan internal research, May 2026). Two Class B towers a block apart can quote you very different numbers on the same afternoon, depending on the landlord’s current vacancy and whether they like your credit. In this tier, touring beats averages, and negotiating pays off. A classic example is the Chanin Building at 122 East 42nd Street.
East of the terminal, along Lexington and Third, is where Grand Central gets affordable. It’s mostly older prewar and postwar elevator buildings that haven’t been renovated in a while, plain and practical. With submarket vacancy at 16.6% (Cushman & Wakefield, Q3 2026), this is still where you have the most leverage. It works for small businesses, early-stage startups, medical and dental practices, nonprofits, and back-office operations that want the commute without the trophy bill.
Two things are worth knowing before you sign here. First, a lot of this space comes as a sublease, and sublets can be the fastest, cheapest way into the neighborhood if the term fits. Second, almost every NYC landlord will want a security deposit and, for smaller or newer companies, a Good Guy Guarantee. Understand both before you negotiate, because that’s where a lot of the risk and cost sit. The big brokerages don’t publish a separate Class C average for Grand Central, so anyone who quotes you a single Class C number is guessing. The tier description here is Metro Manhattan internal research (May 2026).
This is where most tenants lose the most money. They negotiate the asking rent, win a few dollars, and sign without pushing hard on free rent or the build-out allowance, which is where most of the value is. Who pays for the build-out is negotiable, and in a submarket with 16.6% vacancy you still have more room than you think (our explainer on who pays for an office build-out walks through it). The ranges below are typical-market figures from our recent deals (Metro Manhattan internal research, May 2026), assuming a 5- or 10-year term. For a benchmark, CBRE’s third-quarter Midtown report puts the average package on direct new leases of raw space of 25,000 SF or more, with terms of ten years or longer, at 17 months of free rent and $151/SF in improvement allowance. Shorter terms get smaller packages and longer terms get bigger ones. Our breakdown of 3-year, 5-year, or 10-year lease terms covers the trade-offs.
| Tier | Free Rent | Tenant Improvement Allowance | Notes |
|---|---|---|---|
| Trophy and premium Class A | 8 to 12 months free | TI $100 to $160/SF | The tightest concessions in the submarket, because there's often a tenant lined up behind you. |
| Standard Class A | 12 to 16 months free | TI $80 to $120/SF | The best balance of a real Grand Central address and real concessions. |
| Class B | 14 to 18 months free | TI $60 to $90/SF | Spec suites widely available. Take a 10-year term and this tier still has serious leverage. |
| Class C and value | 12 to 18 months free | TI $40 to $70/SF | Many landlords will hand you a turnkey, fully built-out suite, so you can sign one month and move in the next. |
Typical-market figures from recent Metro Manhattan deals, assuming a 5- or 10-year term (Metro Manhattan internal research, May 2026). For a benchmark, CBRE's third-quarter Midtown report puts the average package on direct new leases of raw space of 25,000 SF or more, with terms of ten years or longer, at 17 months of free rent and $151/SF in improvement allowance (CBRE, Manhattan Midtown Office Figures Q3 2026).
One more thing: net effective rent usually lands well below the face rent a landlord first quotes. Working it out takes about ten minutes, and it can be the difference between a fine deal and a great one. Our concessions explainer walks through how it works.
Tenants cluster around the terminal by industry, and not by accident. Finance wants the Park Avenue frontage, law wants the 42nd Street towers, and headquarters with lots of commuters want to sit as close to the trains as the budget allows. Match your industry, headcount, and budget to the right sub-area, and the search gets much smaller. The table below shows where each industry fits.
| Industry | Best-Fit Sub-Areas | Inventory / Class | Rent Tier | Example Buildings |
|---|---|---|---|---|
| Hedge Funds / PE / Asset Management | Vanderbilt core, Park Avenue frontage | Trophy supertall and premium prewar | Trophy | One Vanderbilt, 245 Park, 280 Park |
| Large Banks / Financial Services | Park Avenue frontage, Vanderbilt core | Trophy and premium Class A | Trophy / A | One Vanderbilt, 200 Park (MetLife), 245 Park |
| Big Law / International Law | Park Avenue frontage, 42nd Street spine | Trophy and renovated Class A | Trophy / A | One Vanderbilt, 230 Park (Helmsley), 245 Park |
| Mid-Market & Boutique Law | 42nd Street spine, Madison side streets | Renovated Class A and B | Class A / B | One Grand Central Place, Chanin (122 E 42nd), Graybar (420 Lex) |
| Finance / Trading (midsize) | 42nd Street spine, Park Avenue frontage | Class A and renovated B | Class A / B | 100 Park, 101 Park, 90 Park |
| Technology / SaaS / AI | Vanderbilt core (flagships), Madison side streets | Trophy floors and renovated Class B | Mixed | One Vanderbilt, 335 Madison, 275 Madison |
| Healthcare / Medical Offices | Lexington & Third value, Madison side streets | Class B and C | Class B / C | 370 Lexington, 150 E 42nd, 10 Grand Central (155 E 44th) |
| Professional Services / Consulting | 42nd Street spine, Madison side streets | Class A and B | Class A / B | One Grand Central Place, 270 Madison, 425 Lexington |
| Nonprofits / Associations | Lexington & Third value | Class B and C | Value | 370 Lexington, 750 Third, 630 Third |
| Startups / Small Business (<20 ppl) | Lexington & Third value, Madison side streets | Class B and C side-street inventory | Value | 370 Lexington, 750 Third, 140 E 45th (2 Grand Central) |
Vertical landing pages: Financial Services, Law Firm Offices, Startup & Tech Space, Medical Offices. Sub-area and class fits are Metro Manhattan internal research (May 2026).
Running a small team? Grand Central isn’t the obvious budget pick, since the cheapest rents in Manhattan are elsewhere. But the value buildings east of the terminal hold up well once you factor in what you save on everyone’s commute. If you want to compare, our guide to the 5 top neighborhoods for small businesses lays out the trade-offs, and if you’re coming out of a coworking space, our guide to scaling from coworking to your own office walks through it. And if what you really want is exposed-brick loft space, that is a Midtown South search, so start in Chelsea or SoHo, not here.
If your last Grand Central tour was pre-2020, the picture in your head is wrong. One Vanderbilt opened and reset the ceiling, and the older Class A towers around the terminal started writing big checks because their neighbor did. Amenities are a recruiting tool now: if you want your team riding the train in three days a week, the building has to give them a reason. Three tiers to expect:
Trophy tier (One Vanderbilt): A 30,000 SF amenity floor, Michelin-starred dining from Daniel Boulud, the Summit observation deck, tenant lounges and fitness, smart-building infrastructure, and a private entrance directly into Grand Central. It’s the top of the New York market.
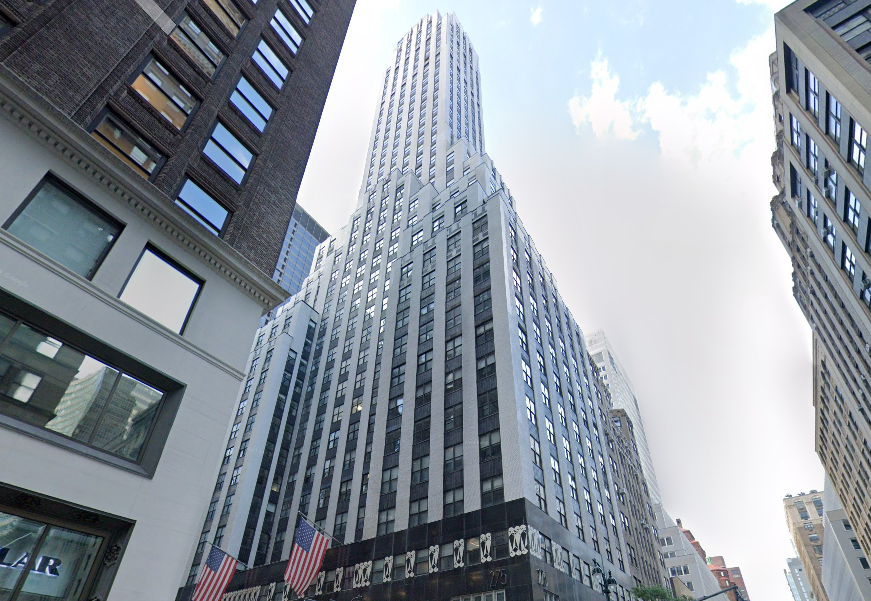
Class A core (MetLife Building, Helmsley Building, 245 Park, One Grand Central Place, the Graybar Building): Renovated lobbies, tenant-only amenity floors added during the 2018 to 2024 capex cycle, on-site fitness and conferencing, ground-floor retail and dining, and in several cases direct interior access to the terminal.
Class B and value tier (370 Lexington, 750 Third, the Chanin Building, side-street Madison stock): Prewar character, big windows, attended lobbies, tenant-controlled HVAC, and a growing number of fully built-out spec suites with furniture and cabling already in place so you can move in fast.
Ground-floor and concourse space around the terminal is some of the highest-traffic retail space in the city, feeding off hundreds of thousands of daily commuters. If you’re after a storefront rather than a floor upstairs, that’s a different search, and a good one with this much foot traffic.
Who owns your building matters as much as which building you pick, because every major Grand Central landlord negotiates differently. SL Green, the city’s largest office landlord with more than 25 million SF, owns One Vanderbilt and a lot of the buildings around the terminal, and it moves fast and pushes hard. Tishman Speyer and RXR hold the Park Avenue frontage. Empire State Realty Trust will take a 2,500 SF tenant seriously when some owners won’t even take the meeting. A good broker knows what you’re walking into. Background reading: the biggest commercial real estate landlords in NYC. Several of these owners also hold much larger portfolios downtown, where the same dollar buys more space.
| Landlord | Notable Grand Central Properties | Approx. Portfolio | Typical Lease Profile |
|---|---|---|---|
| SL Green Realty | One Vanderbilt, the Graybar Building (420 Lexington), 245 Park (partial), 100 Park Avenue | ~25M SF (NYC’s largest office landlord) | 10,000+ SF, 10+ year |
| Tishman Speyer | 200 Park Avenue (the MetLife Building) | ~15M SF Midtown | 10,000+ SF |
| RXR Realty | 230 Park Avenue (the Helmsley Building), 175 Park Avenue (JV, under development) | ~7M SF Midtown | 5,000+ SF |
| Milstein Properties | 22 Vanderbilt (335 Madison Avenue) | Single-asset focus near the terminal | 5,000+ SF |
| Empire State Realty Trust | One Grand Central Place (60 East 42nd Street) | ~8M SF Midtown | 2,000+ SF |
| TF Cornerstone | 175 Park Avenue (JV, under development) | Mixed-use developer | Pre-development |
| JPMorgan Chase (owner-occupier) | 270 Park Avenue (global HQ, adjacent) | 2.5M SF owner-occupied | Owner-occupied |
Portfolio figures are approximate and weighted toward Midtown holdings. Several owners listed (SL Green, Tishman Speyer, RXR) hold substantially larger portfolios across Midtown, Midtown South, and Downtown. 270 Park Avenue is an adjacent Park Avenue address occupied by its owner, JPMorgan Chase, and is not available to lease; it is included for orientation. The Chrysler Building (405 Lexington) is omitted from this table because its ownership is currently in dispute. Metro Manhattan internal research (May 2026).
Transit is the main reason to be at Grand Central, and it’s the strongest return-to-office argument in Manhattan. The terminal puts Metro-North’s Hudson, Harlem, and New Haven lines, the Long Island Rail Road via Grand Central Madison, and the 4, 5, 6, 7, and S subway lines under one roof, with the B, D, F, and M a short walk west. Most of your team can get here without a transfer. Send the skeptics our Commute Calculator with their home address, and let the numbers make the case.
| From | To Grand Central | Mode |
|---|---|---|
| Stamford, CT | 50 to 60 min | Metro-North New Haven Line |
| White Plains, NY | 35 to 45 min | Metro-North Harlem Line |
| Hicksville, NY (Long Island) | 30 to 40 min | LIRR to Grand Central Madison |
| Jamaica, Queens | 20 to 25 min | LIRR to Grand Central Madison |
| Newark, NJ | 25 to 35 min | NJ Transit to Penn + S or 4/5/6 |
| Hoboken, NJ | 20 to 30 min | PATH to 33rd St + 6 train |
| Long Island City, Queens | 8 to 15 min | 7 train |
| Downtown Brooklyn | 20 to 28 min | 4 or 5 train |
| Williamsburg, Brooklyn | 22 to 30 min | L + 4/5/6 |
| Financial District | 12 to 18 min | 4, 5, or 6 train |
Cushman & Wakefield’s third-quarter 2026 numbers put the Grand Central submarket’s overall asking rent at $76.83/SF, with Class A at $85.34/SF. Savills, which tracks a different set of buildings and quotes gross rents, put Grand Central at $87.57/SF for the same quarter. The range underneath is wide: JLL’s third-quarter research reported a lease at One Vanderbilt at $345/SF, while suites we’ve listed this year in older buildings near the terminal asked about $49 to $66/SF.
One Vanderbilt is a 2020-built, 1,401-foot supertall sitting directly on top of the terminal, with a private train-hall entrance, a 30,000 SF amenity floor, and Michelin-starred dining. There’s very little space like it. Nscale signed there at $320/SF in the first quarter of 2026 (JLL via Commercial Observer, April 2026), and JLL’s third-quarter research reported Sentinel signing at $345/SF. The surrounding Class B and C towers are a completely different vintage and price tier, which is why the blended submarket average looks moderate.
The value lane runs east of the terminal along Lexington and Third Avenues, where older Class B and C towers carry the submarket’s highest vacancy and most negotiable rents (Metro Manhattan internal research, May 2026). Cushman & Wakefield’s third-quarter 2026 numbers put Grand Central’s vacancy at 16.6%, down from 18.5% in the first quarter. Tenants in these buildings still have leverage on free rent and build-out allowances, though less than they had in the spring.
The Vanderbilt trophy core and the Park Avenue frontage wrapping the terminal carry the highest rents (Metro Manhattan internal research, May 2026). CBRE’s third-quarter 2026 figures put its Park Avenue district at $112.90/SF with 6.2% of space available, and JLL’s third-quarter research reported a lease at One Vanderbilt at $345/SF. Commercial Observer reported in October 2026 that the citywide high is now $375/SF, for the penthouse at 625 Madison Avenue.
Cushman & Wakefield’s third-quarter 2026 numbers put Grand Central’s vacancy at 16.6%, below the Manhattan average of 18.6% and the Midtown average of 17.0% on the same measure. CBRE, which measures availability (space on the market, including sublets) rather than vacancy, put its Grand Central district at 12.5% for the quarter. The figure reflects a barbell: near-zero vacancy in trophy product at One Vanderbilt and the tight Park Avenue frontage, against much higher vacancy in older Class B and C stock east of the terminal.
Carlyle took 150,036 SF at 245 Park Avenue on a 10-year lease in March, the same month TD Securities expanded to 181,447 SF at 125 Park Avenue (Commercial Observer). In September, Nearwater Management moved from One Vanderbilt to the full 28th floor at 245 Park, and JLL’s third-quarter research reported Sentinel signing at One Vanderbilt at $345/SF. Through September, Cushman & Wakefield counted about 3.3 million SF of new leasing in the Grand Central submarket this year, not counting renewals.
Class generally tracks a building’s age, systems, and prestige: trophy and Class A around Grand Central means One Vanderbilt and the renovated Park Avenue and 42nd Street towers, while Class B and C means the older, often prewar stock east of the terminal. The letter affects price, amenities, and how the space shows, but a well-renovated Class B floor here can rival Class A elsewhere. Our explainer on what makes a building Class A, B, or C breaks down the distinctions.
The district is being physically rebuilt around the station, enabled by the Midtown East rezoning. JPMorgan Chase’s new 2.5M SF global headquarters at 270 Park Avenue opened in October 2025 (New York YIMBY, 2025). Next up is 175 Park Avenue, RXR and TF Cornerstone’s roughly 2.9M SF Project Commodore tower (a mix of Class A office and a new Grand Hyatt), which NYC EDC and New York YIMBY reported in early 2026 was expected to begin construction in mid-2026, on the site of the former Grand Hyatt beside the terminal (NYC EDC, January 2026; New York YIMBY, April 2026).
Grand Central is served by Metro-North (Hudson, Harlem, and New Haven lines), the Long Island Rail Road via Grand Central Madison (opened January 2023), and the 4, 5, 6, 7, and S subway lines, with the B, D, F, and M a short walk west. Grand Central Madison carries roughly 70,000 LIRR riders on a typical weekday, about 40% of Manhattan-bound LIRR traffic (MTA, 2025). Several buildings connect directly into the terminal, including One Vanderbilt and the Graybar Building.
It’s arguably the best in the region. The terminal is the single point where Metro-North and the LIRR meet the subway, so employees from Connecticut, Westchester, the Hudson Valley, and Long Island can often reach the office without a transfer. For return-to-office plans that depend on a tolerable commute, that reach is the entire argument.
Most Grand Central inventory never appears on public search platforms, and a broker can get you into it. A good one also knows which landlords are dealing, which buildings have spec suites, and where asking rents have room to move. Brokerage commissions are paid by the landlord, so the cost to the tenant is effectively zero. Before you tour, it’s worth reviewing the essentials to ask before leasing NYC office space and assembling a strong tenant proposal package so your offer competes on more than rent.
Accessibility Tools