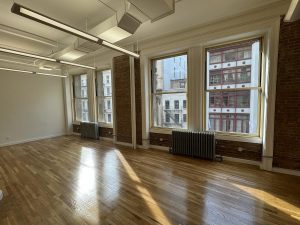

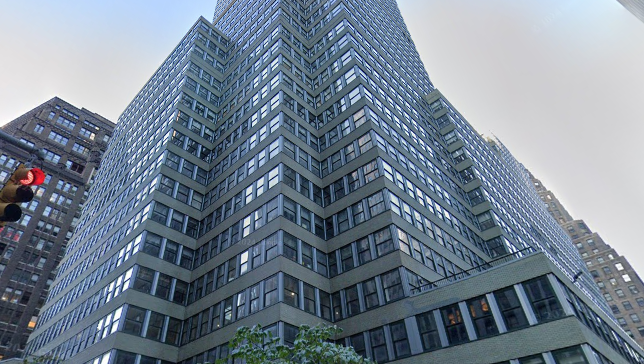

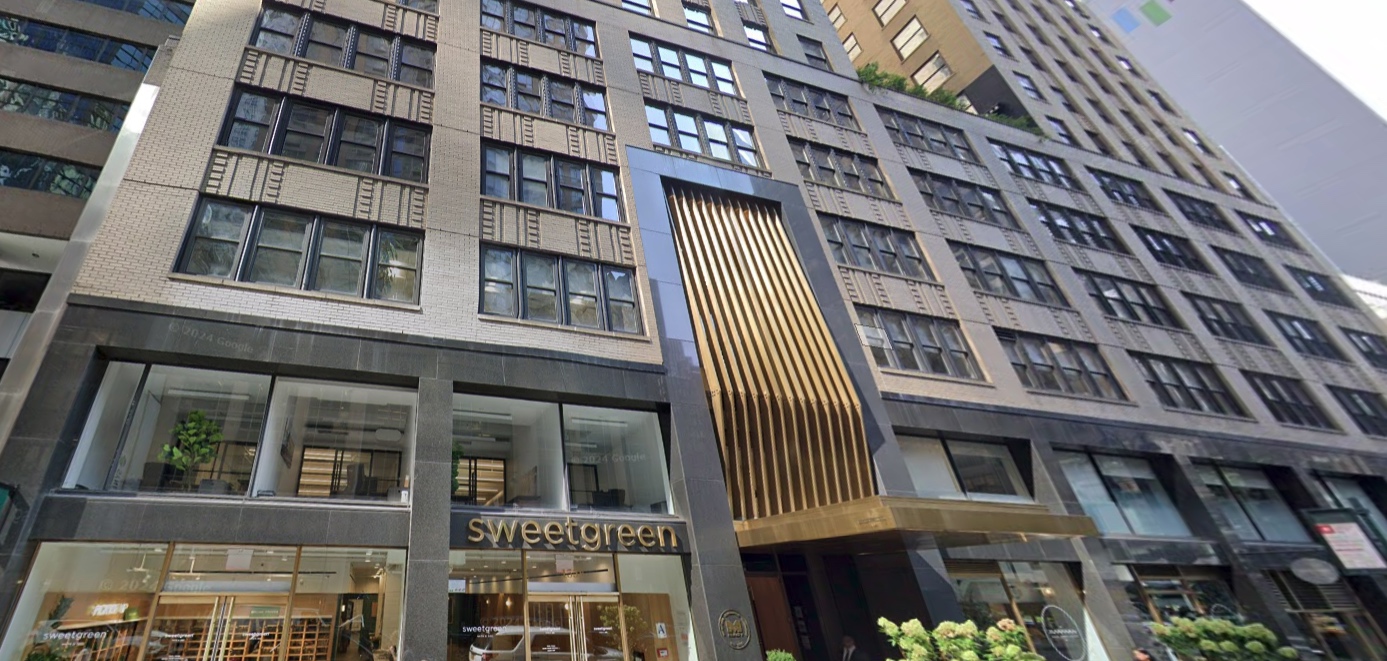


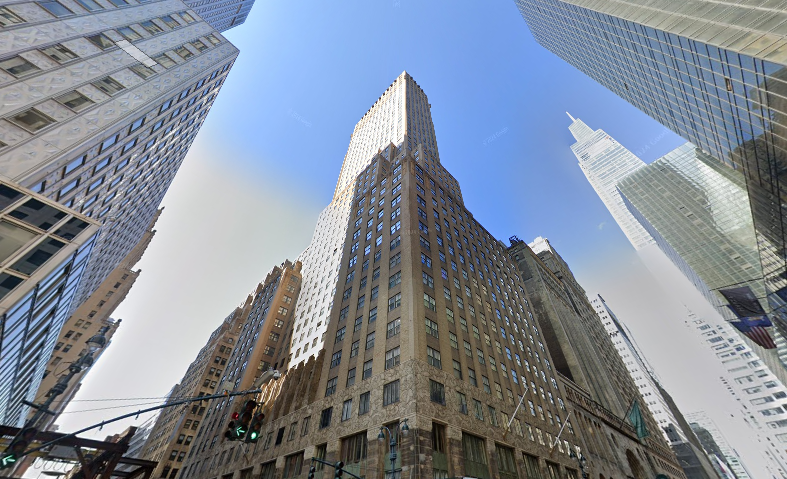


Fifth and Madison are the addresses people picture when they think of a New York office. One made the adv...
Learn more about 5th Avenue/Madison Avenue


Midtown is the biggest office market on the continent. About 258 million SF by Cushman & Wakefield’s count. 13 submarkets. Hudson Yards to the UN, Columbus Circle down to Penn Station. And inside that one giant market, a Park Avenue trophy floor and a Murray Hill loft can sit on the same subway line at totally different prices. So when somebody tells you “Midtown is expensive,” they’re being lazy. Midtown is whatever you make it. Where you land matters way more than whether you land here.
Quick read on the third quarter of 2026: Manhattan just had its busiest first nine months of leasing since 2000, 32.86 million SF. Availability fell to 12.4%, the 10th straight quarter of tightening or holding steady, and Midtown’s is down to 11.9% (Colliers, Q3 2026). Midtown asking rents climbed to $78.83/SF, and Class A hit $90.57/SF, its highest since 2008 (Cushman & Wakefield, Q3 2026). The takeaway is simple: if you’ve been waiting for landlords to get desperate, that’s not happening. They’re not even nervous anymore.
Many of our clients are teams of 5 to 30 people, not law firms renewing on 447,698 square feet in Times Square. The big leases get the headlines, but plenty of older Midtown buildings lease suites of 1,000 to 7,500 square feet, and many of those come prebuilt.
Plan on about 150 to 250 square feet per person, depending on how many private offices you want. That works out to roughly 750 to 1,250 square feet for 5 people, 2,250 to 3,750 for 15, and 4,500 to 7,500 for 30. Our office space calculator will give you a closer number before you tour.
Where you land in Midtown changes the rent more than anything else. Small suites listed on our site over the past year asked about $34 to $39 a foot in the Garment District and $49 to $60 around Murray Hill and Grand Central, while a renovated tower like 3 Park Avenue asked $82. At $50 a foot, a 2,400-square-foot office for about 12 people costs about $10,000 a month before electricity.
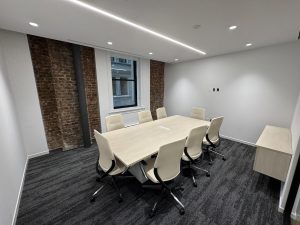
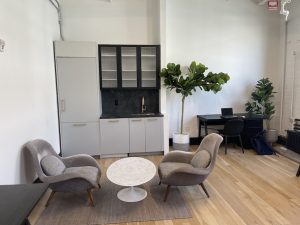
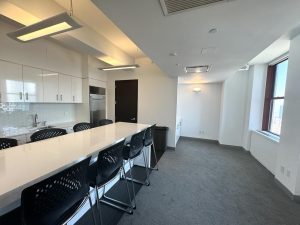
Ask about prebuilt suites. Landlords build them out ahead of time with offices, a conference room, and a kitchen, so you can sign and move in within weeks instead of waiting months for construction.
Where to start, by submarket:
For two to five people, a private office in a coworking space can cost less than a lease of your own. Our coworking page covers the options across Midtown.
Still choosing a neighborhood? We compare the best NYC neighborhoods for small businesses in a separate guide. If you’re outgrowing a coworking membership, we also cover how to move from coworking into an office of your own.
| Submarket | Tier | Profile | Best For |
| Hudson Yards | Trophy | New trophy Class A | Finance, tech, law |
| Plaza District | Trophy | Trophy Class A | Hedge funds, PE, banking |
| Park Avenue | Trophy | Trophy Class A | Finance, asset management, law |
| 5th Avenue / Madison Avenue | Trophy | Trophy Class A and B | Luxury, finance, PR, advisory |
| Penn Station / Garment District | Mixed | Class A, B, and C | Fashion, media, startups |
| 6th Ave / Rockefeller Center | Class A | Class A | Media, law, professional services |
| Bryant Park | Class A | Class A | Law, finance, consulting |
| Grand Central | Class A | Class A and B | Finance, law, commuter HQs |
| Times Square / West Side | Class A | Class A and B | Media, entertainment, tech |
| Midtown East | Class A | Class A and B | Consulting, law, medical |
| Columbus Circle | Class A | Class A and B | Media, finance, advisory |
| Murray Hill | Value | Class B and C | Startups, small business, medical |
| United Nations | Value | Class B and C | Nonprofits, NGOs, diplomatic |
The most common mistake tenants make in Midtown is shopping it like one market. It isn’t. It’s thirteen markets stacked on top of each other, and the deal on Park Avenue has nothing to do with the deal in Murray Hill. Get the submarket right and the rest of the search gets easy. Get it wrong and you’ll spend three months touring buildings that were never going to work.
So what’s actually happening right now? Manhattan tenants signed 32.86 million SF through September, the strongest first nine months since 2000. Availability fell to 12.4%, the 10th straight quarter of tightening or holding steady, and the amount of space on the market is the lowest since August 2020 (Colliers, Q3 2026). Cushman & Wakefield has the Manhattan average asking rent at $74.37/SF, the highest since May 2019. This isn’t one good quarter. It’s a ten-quarter trend that just keeps showing up in the data.
Midtown specifically: $78.83/SF overall and $90.57/SF Class A, the highest Class A average since 2008 (Cushman & Wakefield, Q3 2026). Vacancy fell to 17.0%, the lowest since early 2021, and it’s down from a year ago in all nine of Cushman & Wakefield’s Midtown submarkets. Class A slipped sixteen cents in the first quarter. It’s up more than $5 a foot since.
Want the real proof? Look at who’s signing. This year, Proskauer Rose renewed 447,698 SF at 11 Times Square and Morgan Lewis took 210,000 SF at 1251 Avenue of the Americas (Cushman & Wakefield, Q3 2026), and General Atlantic took about 151,000 SF at 625 Madison Avenue (CBRE, Q3 2026). Back in January, Deloitte’s 807,000 SF commitment at 70 Hudson Yards was reported as the priciest lease in NYC since the pandemic, at over $2.6 billion across nearly 22 years (CoStar Group via CompStak, January 2026). When the smartest, most over-resourced tenants in the world are signing 20-year leases at the top of the market, you don’t argue with the chart.
It depends on where in Midtown and what class of building. Anyone giving you a single number for “Midtown rent” doesn’t know what they’re talking about. The range is huge. Class C in Murray Hill at the bottom. Castle Hook Partners at $375/SF for the penthouse at 625 Madison Avenue at the top, the highest office rent New York has recorded (Commercial Observer, October 19, 2026). The Class A average is $90.57/SF (Cushman & Wakefield, Q3 2026), but that average is hiding more than it’s showing.
Start with this question, because it changes everything: do you actually need a trophy address? Hedge funds, Big Law, anyone whose clients walk through your lobby every week, yes. Most other tenants, no. Most of Midtown’s leasable inventory is Class B, sitting in Grand Central, Times Square / West Side, Penn Station / Garment District, and Murray Hill. Overall Midtown rent is $78.83/SF (Cushman & Wakefield, Q3 2026). Class B prices below that. Same neighborhood. Same subway. Much better deal. The gap between the overall average and Class A alone is $11.74 a foot, about $58,700 a year on a 5,000-square-foot office. Skipping trophy is the move most savvy tenants make, and most of them don’t regret it. Not sure how much space you actually need? Run your headcount through our Office Space Calculator before you tour anything.
| Submarket | Class A Profile | Class B / C Coverage | Availability | Typical Square Footage for New Leases | Tier |
|---|---|---|---|---|---|
| Hudson Yards | Premium / Trophy | Limited Class B; no Class C | ~10 to 13% | 20,000 to 100,000+ SF | Trophy |
| Plaza District | Premium / Trophy | Limited Class B; minimal Class C | ~10 to 11% | 10,000 to 50,000+ SF | Trophy |
| Park Avenue | Premium / Trophy | Some Class B; minimal Class C | ~10 to 13% | 10,000 to 50,000+ SF | Trophy |
| 5th Ave / Madison Ave | Premium / Trophy | Class B inventory available | ~12 to 14% | 5,000 to 30,000 SF | Trophy |
| 6th Ave / Rockefeller | Class A core | Class B inventory available | ~12 to 14% | 5,000 to 40,000 SF | Class A |
| Bryant Park | Class A core | Class B inventory available | ~12 to 14% | 5,000 to 30,000 SF | Class A |
| Grand Central | Class A core | Class B and Class C available | ~13 to 14% | 2,500 to 40,000 SF | Class A |
| Times Square / West Side | Class A core | Class B and Class C available | ~13 to 15% | 5,000 to 50,000 SF | Class A |
| Midtown East | Class A core | Class B and Class C available | ~15 to 17% | 2,000 to 15,000 SF | Class A |
| Columbus Circle | Class A core | Class B and Class C available | ~13 to 15% | 5,000 to 25,000 SF | Class A |
| Penn Station / Garment | Class A available | Class B and Class C dominate | ~9 to 11% | 2,500 to 25,000 SF | Mixed |
| Murray Hill | Limited Class A | Class B and Class C dominate | ~22 to 25% | 1,500 to 10,000 SF | Value |
| United Nations | Limited Class A | Class B and Class C dominate | ~20 to 22% | 2,000 to 15,000 SF | Value |
| Midtown Average | $90.57 Class A | $78.83 overall district average | ~12 to 14% | Varies | Mixed |
Midtown Class A average asking rent of $90.57/SF and Midtown overall asking rent of $78.83/SF from Cushman & Wakefield, Manhattan Office MarketBeat Q3 2026. Submarket-level Class A profiles, Class B and C coverage descriptors, and availability ranges are Metro Manhattan internal research (May 2026). Cushman & Wakefield, CBRE, and Savills publish Midtown submarket figures in their Q3 2026 reports, but their boundaries don't match these thirteen rows.
Class A averaged $90.57/SF in the third quarter of 2026, up $2.07 in three months and the highest since 2008 (Cushman & Wakefield). Savills has Midtown Class A above $100 for the first time, at $102.36/SF. Walk into a Class A tour right now expecting one thing: landlords who know exactly what their buildings are worth. They’re not in a hurry. Lead with your credit, your term, and a clean ask. Show up like it’s 2023 and you’ll get a 2023 reception, which is to say not a warm one.
Trophy is its own animal. JLL has Manhattan trophy vacancy at a cycle-low 4.9% and trophy asking rents averaging $137.09/SF, and CBRE says Midtown trophy rents are up 12% in a year (Q3 2026). Supply is shrinking and prices are rising. If you need a trophy address, the hard part is finding the space, so start early rather than waiting for someone to give space back. For a deeper look at what actually separates trophy buildings from regular Class A, see our piece on how trophy buildings set themselves apart in NYC.
Where trophy actually lives: Hudson Yards (10, 30, 50, 55, 70 Hudson Yards), Park Avenue (One Vanderbilt, 425 Park, 280 Park, 200 Park, 399 Park), 5th and Madison (550 Madison, 425 Madison), the Plaza District (9 West 57th, the GM Building), and 6th Avenue / Rockefeller Center (1271 Sixth Avenue (Time-Life Building), 1221 Sixth Avenue, 30 Rockefeller Plaza). The icons: the Empire State Building and the Chrysler Building. For a deeper rundown, see our list of the top 10 Class A office buildings in Midtown.
Midsize firm? Growing but not crazy yet? Don’t need to impress a hedge fund every Tuesday? This is your tier, and honestly, it’s where most Midtown leases get signed. Class B holds most of Midtown’s leasable space. The good ones cluster in Grand Central, Midtown East, Columbus Circle, Bryant Park, and parts of Times Square / West Side. Names you’d recognize: One Grand Central Place, The Chanin Building, 30 Rockefeller Plaza, 1290 Avenue of the Americas. A lot of these landlords have spent real money on renovations and prebuilt spec suites in the last five years. Walk into a 2026 Class B building and it often looks like a 2018 Class A. Big difference for your team. Small difference for your bill. Not bad. (Quick refresher on the class system here.)
On pricing, Midtown overall is $78.83/SF in the third quarter of 2026 (Cushman & Wakefield). Class B typically prices below that, and how far below depends entirely on the submarket and the building (Metro Manhattan internal research, May 2026). Across Manhattan, Avison Young puts the gap between Class A and Class B/C base rents at about $10 a foot (Q3 2026). Two Class B buildings two blocks apart can quote you very different numbers on the same afternoon, depending on the landlord’s vacancy, their mood, and whether they like you. This is the tier where touring beats averages. This is also the tier where negotiation actually pays.
If your priority is keeping costs down and you don’t need a fancy lobby to land your next client, Class C is where you’ll find the deals. Most of it sits in Murray Hill, the UN submarket, parts of Midtown East, and the Penn Station / Garment District. Mostly pre-war elevator buildings that haven’t been renovated in a while. Honest character, no pretense.
Class C works for small businesses, early-stage startups, medical and dental practices, nonprofits, back-office operations, and diplomatic missions. The major brokerages don’t publish a Class C average for Midtown. So if anyone hands you a single “Class C rent” number, they’re guessing or selling you something. The tier description here is Metro Manhattan internal research (May 2026), based on the deals we actually work on.
This is where most tenants give away the most money. They negotiate the asking rent, get a small win and sign. They never push hard on free rent or TI allowance, which is where the real value lives in non-trophy Class A and Class B Midtown deals. The ranges below are typical-market figures from our recent deals (Metro Manhattan internal research, May 2026), assuming a 5 or 10-year term. Shorter terms get proportionally smaller packages. 12 to 15-year terms can pull significantly richer ones. For a benchmark, CBRE puts the average package on big new Midtown leases of raw space (25,000 SF and up, ten-year terms or longer) at 17 months of free rent and $151/SF in improvement money, per its Q3 2026 report. On a 5,000-square-foot office at $78 a foot, each free month is worth about $32,500. If you’re not sure which term length actually fits your business, our breakdown of 3-year, 5-year, or 10-year lease terms walks through the trade-offs. Your actual numbers come down to credit, term, building, and how hard you push.
| Building Class | Free Rent | TI Allowance | Notes |
|---|---|---|---|
| Trophy and premium Class A | 8 to 12 months | $100 to $160/SF | The tightest concessions in Midtown, because there's a tenant lined up behind you. |
| Standard Class A | 12 to 17 months | $80 to $120/SF | The best balance of real Midtown address and real concessions. |
| Class B | 14 to 18 months | $60 to $90/SF | Spec suites widely available. Take a 10-year term and you'll have more negotiating room than anywhere else in the market. |
| Class C | 12 to 18 months | $40 to $70/SF | Often built-out turnkey suites you can sign and move into in 30 days. |
Typical-market figures from recent Metro Manhattan deals (Metro Manhattan internal research, May 2026), assuming a 5 or 10-year term. Shorter terms get proportionally smaller packages; 12 to 15-year terms can pull significantly richer ones. Actual numbers vary by credit, term, building, and negotiation.
One more thing on Class B: net effective rent typically lands well below the face rent your broker first quotes you. It takes about ten minutes to learn, and it’s often worth more than anything you win on the asking rent. Our concessions explainer walks through it.
Industries cluster in Midtown for a reason. Investors find each other on Park Avenue. AI companies pile into Hudson Yards. Fashion sticks to the Garment District. There’s a logic to it, and matching your industry, your headcount, and your budget to the right submarket can save you weeks of touring the wrong buildings. The table below shows where each industry fits.
| Industry | Best-Fit Submarkets | Class Fit | Example Buildings |
|---|---|---|---|
| Hedge Funds / Private Equity / Asset Management | Plaza District, Park Avenue, 5th / Madison | Trophy | 9 West 57th, 425 Park (One Vanderbilt), 280 Park, 590 Madison, 510 Madison |
| Large Banks / Financial Services | Park Avenue, Hudson Yards, Plaza District | Trophy | 270 Park, 399 Park, 70 Hudson Yards, 660 Fifth Avenue, 200 Park |
| Big Law / International Law Firms | Park Avenue, 6th Ave / Rockefeller, Bryant Park | Trophy / Class A | 1211 Sixth Avenue, 1221 Sixth Avenue, 425 Park, 1271 Sixth Avenue, 45 Rockefeller Plaza |
| Mid-Market Law / Boutique Firms | Grand Central, Bryant Park, Midtown East | Class A / Class B | One Grand Central Place, 230 Park (Helmsley), 122 East 42nd (Chanin), 350 Fifth Avenue |
| Consulting / Big 4 Accounting | Hudson Yards, 6th Ave / Rockefeller, Bryant Park | Trophy / Class A | 70 Hudson Yards (Deloitte), 30 Rockefeller Plaza, 1271 Sixth Avenue, 1166 Sixth Avenue |
| Technology / SaaS / AI | Hudson Yards, Times Square / West Side, Penn Station | Class A / Trophy | 55 Hudson Yards, 11 Times Square, 5 Manhattan West, 30 Hudson Yards |
| Media / Entertainment / PR | Times Square, 6th Ave / Rockefeller, Columbus Circle | Class A | 1271 Sixth Avenue, 1675 Broadway, 1700 Broadway, 11 Times Square, Hearst Tower |
| Advertising / Marketing / Creative | Bryant Park, 6th Ave / Rockefeller, Penn Station | Class A / Class B | 1040 Sixth Avenue, 1185 Sixth Avenue, 1411 Broadway, 1411 Sixth Avenue |
| Fashion / Apparel / Wholesale | Penn Station / Garment District | Class B | 1411 Broadway, 1412 Broadway, 530 Seventh Avenue, 1407 Broadway |
| Healthcare / Medical Offices | Murray Hill, Midtown East, Columbus Circle | Class B / Class C | 57 West 57th, 133 East 58th, 200 Central Park South, 120 East 56th |
| Nonprofits / Diplomatic / NGOs | United Nations, Murray Hill, Midtown East | Class B / Class C | 866 UN Plaza, 405 Lexington (Chrysler), 2 UN Plaza, 800 Second Avenue |
| Startups / Small Business (<20 ppl) | Murray Hill, Penn Station, Garment District | Class B / Class C | 3 Park Avenue, 171 Madison, 286 Madison, 370 Lexington Avenue, 202 West 40th |
| Retail / Showroom / Pop-Up | 5th Avenue, Times Square, Madison Avenue | Trophy retail at 5th Avenue 50s, Times Square corners, Madison Avenue 60s |
Metro Manhattan internal research (May 2026).
If you toured Midtown five years ago, the picture in your head is out of date. The amenity game has been transformed. One Vanderbilt opened. Hudson Yards filled in. Manhattan West came online. Older Class A buildings around Grand Central started writing big checks because their neighbors did. Amenities aren’t a perk anymore, they’re a recruiting tool. If you want your team in the office three days a week, the building has to give them a reason to want to be there. Three tiers:
Trophy tier (Hudson Yards, One Vanderbilt, 425 Park, 9 West 57th, 550 Madison): Tenant-only amenity floors, conferencing, lounges, fitness, dining. Private clubs and observation decks (The Summit, Edge). LEED Platinum. Smart-building infrastructure. Direct or near-direct access to Grand Central, Penn Station, or the 7 train.
Class A core (Empire State, Chrysler, One Grand Central Place, 1271 Sixth, 30 Rock): Renovated lobbies, on-site fitness, real conferencing, modernized mechanicals, ground-floor retail and dining, walking-distance transit. Many added tenant-only amenity floors during the 2018 to 2024 capex cycle.
Class B and value tier (3 Park Avenue, 286 Madison, 171 Madison, Garment District lofts): Pre-war character, big windows, customizable build-outs, modest shared amenities. Many landlords now offer fully built-out spec suites with furniture, IT, and turnkey move-in.
See all Midtown buildings or filter active listings by size and price.
Who owns your building matters as much as which building you pick, and most tenants underestimate it. Every major Midtown landlord has a personality, and that personality shows up at the negotiation table. SL Green moves fast and pushes hard. Vornado holds firm and waits you out. Related plays the long game on Hudson Yards. Empire State Realty Trust will take smaller tenants seriously where some of the bigger names won’t even take the meeting. A good broker knows what you’re walking into. Background reading: biggest commercial real estate landlords in NYC.
| Landlord | Notable Midtown Properties | Approx. Midtown Portfolio | Typical Lease Profile |
|---|---|---|---|
| SL Green Realty | One Vanderbilt (425 Park), 919 Third Avenue, 280 Park (partial), 100 Park Avenue, 1185 Sixth Avenue | ~25M SF (NYC's largest office landlord) | 10,000+ SF, 10+ year |
| Vornado Realty Trust | 1 Penn, 2 Penn, Penn 11, 280 Park (partial), 330 Madison | ~20M SF | 15,000+ SF |
| The Related Companies | Hudson Yards complex (10, 30, 35, 50, 55, 70 HY), Manhattan West (partial) | ~18M SF (Hudson Yards / MW) | 20,000+ SF |
| Tishman Speyer | Rockefeller Center (incl. 30 Rock), 1166 Sixth Avenue, 520 Madison, The Spiral (66 Hudson Blvd) | ~15M SF | 10,000+ SF |
| Brookfield Properties | Manhattan West (1, 2, 5 MW), 660 Fifth Avenue, 660 Madison | ~10M SF | 15,000+ SF |
| Boston Properties (BXP) | 399 Park Avenue, 601 Lexington (Citigroup Center), General Motors Building (767 Fifth) | ~10M SF | 10,000+ SF |
| Rudin Management | 345 Park Avenue, 3 Times Square, 32 Sixth Avenue, 560 Lexington, 415 Madison | ~10M SF | 5,000+ SF |
| RXR Realty | 1285 Sixth Avenue, 75 Rockefeller, 230 Park Avenue (Helmsley) | ~7M SF | 5,000+ SF |
| The Durst Organization | One Bryant Park (BoA Tower), 4 Times Square, 1133 Sixth Avenue, 1155 Sixth Avenue | ~10M SF | 10,000+ SF |
| Empire State Realty Trust | Empire State Building, 1400 Broadway, 1350 Broadway, 250 West 57th, 501 Seventh | ~8M SF | 2,000+ SF |
| Fisher Brothers | Park Avenue Plaza (399 Park), 605 Third Avenue, 1345 Sixth Avenue, 299 Park Avenue | ~6M SF | 10,000+ SF |
| Silverstein Properties | 1177 Sixth Avenue, 530 Fifth Avenue, 120 Broadway (also Downtown) | ~4M SF Midtown | 10,000+ SF |
Portfolio figures are approximate and limited to Midtown holdings. Most of these landlords also operate significant inventory in Midtown South, Downtown, and outside Manhattan.
If your team is still pushing back on the office, this might be your strongest counter-argument. Midtown is the most transit-connected office submarket on the planet. Three major hubs (Grand Central, Penn Station, Port Authority Bus Terminal) anchor 14 subway lines, three commuter railroads, PATH to New Jersey, and intercity bus and rail. Most of your team can probably get here without a transfer. That’s a real talking point when you’re trying to win the return-to-office conversation. Use our Commute Calculator to check specific addresses.
| From | To Midtown (Grand Central or Penn) | Mode |
|---|---|---|
| Stamford, CT | 45 to 55 min | Metro-North |
| White Plains, NY | 35 to 45 min | Metro-North |
| Hicksville, NY (Long Island) | 30 to 40 min | LIRR to Grand Central Madison |
| Newark, NJ | 20 to 25 min | NJ Transit to Penn Station |
| Hoboken, NJ | 10 to 15 min | PATH to 33rd St |
| Jersey City (Exchange Place) | 12 to 18 min | PATH to 33rd St |
| Downtown Brooklyn | 20 to 28 min | 2, 3 or 4, 5 to Grand Central |
| Park Slope, Brooklyn | 25 to 35 min | R or 2, 3 to Times Square or Grand Central |
| Williamsburg, Brooklyn | 20 to 28 min | L to Union Square + 4, 5, 6 |
| Long Island City, Queens | 8 to 15 min | 7 to Grand Central or Times Square |
| Downtown Manhattan (Fulton) | 12 to 18 min | 4, 5, 6 |
Cushman & Wakefield’s third-quarter 2026 numbers put Midtown’s average asking rent at $78.83/SF, with Class A at $90.57/SF. CBRE, which tracks only fully modernized buildings, had Midtown at $85.53/SF for the same quarter. Submarket averages in the C&W report ran from $50.92/SF in Times Square South to $132.25/SF on Park Avenue.
Cushman & Wakefield’s third-quarter 2026 report put Midtown Class A asking rents at $90.57/SF, up $2.07 in the quarter and the highest level since 2008. Savills had Midtown Class A above $100/SF for the first time, at $102.36/SF. Trophy space runs higher still: JLL’s third-quarter research put Manhattan trophy asking rents at an average of $137.09/SF (CRE Daily, October 5, 2026).
Cushman & Wakefield’s third-quarter 2026 report put Midtown’s overall average at $78.83/SF but doesn’t break out Class B or Class C. Avison Young’s third-quarter report found Manhattan Class A and Class B/C base rents about $10/SF apart, with net effective rents of about $83/SF for both once concessions are counted (CRE Daily, October 6, 2026). Small suites listed on our site over the past year asked $34 to $39/SF in the Garment District and $49 to $60/SF around Murray Hill and Grand Central.
Cushman & Wakefield’s third-quarter 2026 numbers put Times Square South at the bottom of Midtown at $50.92/SF, with Murray Hill next at $60.59/SF. CBRE’s third-quarter report also had Times Square South as Midtown’s least expensive district, at $60.90/SF. On our own site, small suites in Garment District loft buildings asked $34 to $39/SF over the past year.
Cushman & Wakefield’s third-quarter 2026 numbers put Park Avenue at the top of Midtown at $132.25/SF, followed by Madison / Fifth at $100.29/SF. Savills, which tracks Hudson Yards and the Plaza District separately, put Hudson Yards at $134.45/SF and Plaza South at $128.00/SF. The highest rent on record in New York is now Castle Hook Partners’ $375/SF for the penthouse at 625 Madison Avenue (Commercial Observer, October 19, 2026).
Colliers put Midtown availability at 11.9% in the third quarter of 2026, and Manhattan’s at 12.4%, its 10th straight quarter of tightening or holding steady (Commercial Observer, October 19, 2026). CBRE had Midtown availability at 12.1%, its lowest since the first quarter of 2020. Cushman & Wakefield, which measures vacancy instead, put Midtown at 17.0%, the lowest since the first quarter of 2021.
Proskauer Rose’s 447,698 SF renewal at 11 Times Square was the quarter’s biggest Midtown deal in Cushman & Wakefield’s report, and Havas Health and You renewed and expanded on 254,118 SF at 200 Madison Avenue. The largest new deals were Morgan Lewis’s 210,000 SF at 1251 Avenue of the Americas and Snap’s 198,893 SF sublease at Penn 2. Colliers and Savills also list NBCUniversal’s 244,185 SF renewal at 1221 Avenue of the Americas.
Small businesses (under 5,000 SF) typically find the best Midtown value in Class B and Class C buildings in Murray Hill, Penn Station / Garment District, and on side streets near Grand Central. Buildings include 3 Park Avenue, 171 Madison, 286 Madison, 70 West 36th, 202 West 40th, and 248 West 35th (Metro Manhattan internal research, May 2026). Many landlords offer fully built-out spec suites with flexible 3 to 5 year terms.
Midtown is served by 14 subway lines (1, 2, 3, 4, 5, 6, 7, A, C, E, N, Q, R, W, plus the S shuttle), Metro-North, the Long Island Rail Road (at both Penn Station and Grand Central Madison, opened January 2023), NJ Transit, Amtrak, PATH, NYC Ferry, and the Port Authority Bus Terminal. Grand Central, Penn Station, and Port Authority each anchor multi-line subway hubs.
Cushman & Wakefield counted 2.8 million SF of AI-related leasing in Manhattan through the third quarter of 2026, nearly triple the full-year 2025 total, though still only 11.7% of all new leasing. The quarter’s largest AI lease, Anthropic’s 465,630 SF at 330 Hudson Street, went to Midtown South. In Midtown, Nscale signed at $320/SF at One Vanderbilt in the first quarter of 2026 (JLL, Q1 2026).

Fifth and Madison are the addresses people picture when they think of a New York office. One made the adv...
Learn more about 5th Avenue/Madison Avenue
Stand at 50th and Sixth, where a tour bus and a managing partner fight for the same crosswalk. This is th...
Learn more about 6th Avenue/Rockefeller Center
Bryant Park is the rare Midtown address that looks onto a real park instead of another building. Nine and...
Learn more about Bryant Park
Columbus Circle is the rare Midtown address where you can walk out of a meeting and into Central Park. Pe...
Learn more about Columbus Circle
Midtown East is the New York you've seen in a hundred establishing shots: the Chrysler Building's steel c...
Learn more about East Side
This submarket is really two markets sharing one name. On top of Penn Station, Vornado spent the better p...
Learn more about Garment District
Most people pick Grand Central for one reason: the commute. Then they sign a lease and discover everythin...
Learn more about Grand Central
Everybody's been to Herald Square. You just probably weren't thinking about office space when you were th...
Learn more about Herald Square
Walk west on 33rd Street and the city flips. The brick and the fire escapes drop away, and you hit a wall...
Learn more about Hudson Yards
Murray Hill sits just below and east of Grand Central, a pocket of brownstones, walk-ups, and prewar offi...
Learn more about Murray Hill
Park Avenue is the address American business built for itself. Fourteen blocks of glass and bronze runnin...
Learn more about Park Avenue
This submarket is really two markets sharing one name. On top of Penn Station, Vornado spent the better p...
Learn more about Penn Station
By CBRE's count, the Plaza District is the most expensive office market in New York. It covers Park Avenu...
Learn more about Plaza District
Everybody knows Times Square. Almost nobody thinks of it as an office market, which is exactly the mistak...
Learn more about Times Square
Three blocks east of Grand Central, Midtown finally goes quiet. The crowds thin, the sidewalks open up, a...
Learn more about United Nations
Everybody knows Times Square. Almost nobody thinks of it as an office market, which is exactly the mistak...
Learn more about West SideAccessibility Tools