



7 Hidden Charges When Leasing Office Space
Nobody likes surprises when it comes to hidden costs.


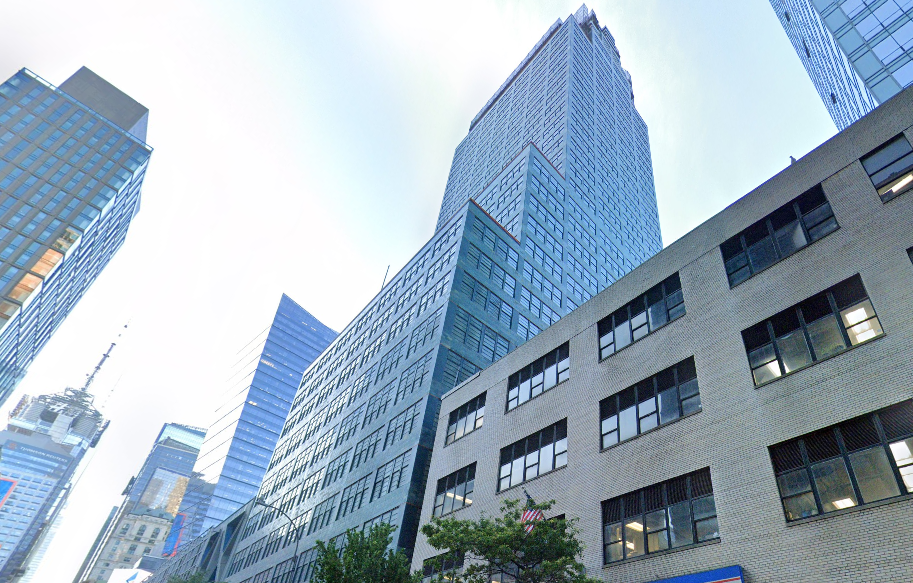
This submarket is really two markets sharing one name. On top of Penn Station, Vornado spent the better part of a decade and roughly $750 million turning a tired tower into PENN 2, and the rents up there now start around $109/SF (Vornado, Q4 2025 earnings, February 2026). Walk ten minutes north into the Garment District and you’re touring 1923 fashion lofts where a 1,300 SF suite can ask $37/SF. Same submarket. Same subway lines. Wildly different worlds. So when somebody quotes you “the Penn Station rent,” ask them which half they mean.
Quick read on the wider market through September: Manhattan just had its busiest first nine months of leasing since 2000, and availability fell to 12.4% in the third quarter, from 13.0% in the second (Colliers, via Commercial Observer). The Penn District is riding that wave hard, and CBRE has its Penn District/Hudson Yards district at 5.2% available, its lowest since 2000. The Garment District is quieter, and that’s exactly where the deals still are. Cushman & Wakefield’s third-quarter averages put the two halves about $45/SF apart: $96.17/SF in its Penn Station submarket and $50.92/SF in Times Square South, which covers most of the Garment District. On a 3,000 SF office, that gap is worth about $136,000 a year.
Many of our clients are teams of 5 to 30 people, not tech companies taking 62,000 SF floors. Those are the leases that make news here: Veeva and Altana each took a full floor at PENN 2 in June, and Snap took about 199,000 SF there on a sublease from Verizon. Small teams do better on the Garment District side streets, where loft buildings lease suites of about 1,000 to 3,600 SF and some come prebuilt.
Plan on about 150 to 250 square feet per person, depending on how many private offices you want. That works out to roughly 750 to 1,250 square feet for 5 people, 2,250 to 3,750 for 15, and 4,500 to 7,500 for 30. The office space calculator in the pricing section below will give you a closer number before you tour.
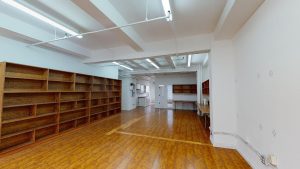
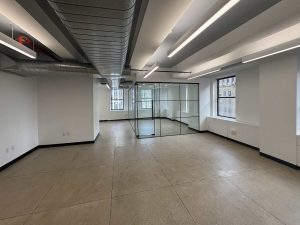
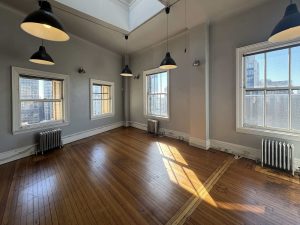
The side-street lofts are where small teams get the most for their money. Suites listed on our site this year in four buildings between Seventh and Eighth Avenues asked about $33 to $39/SF. At $36/SF, a 2,400 SF suite for about 12 people costs about $7,200 a month before electricity. Full floors at PENN 2 were marketed at about $110 to $125/SF this year.
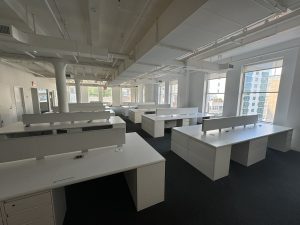
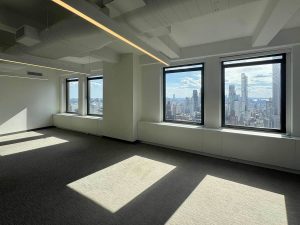
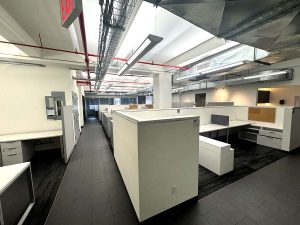
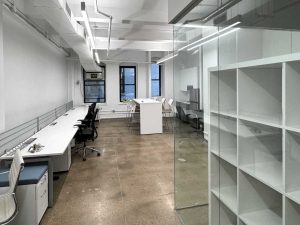
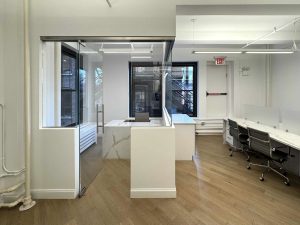
Ask about prebuilt suites. Landlords build them out ahead of time with offices, a conference room, and a pantry, so you can sign and move in within weeks instead of waiting months for construction. Some of the suites below came that way.
Buildings to start with:
For two to five people, a private office in a coworking space can cost less than a lease of your own. Our coworking overview, linked in the industry guide below, covers the options.
| Zone | Tier | Profile | Best For |
|---|---|---|---|
| The Penn District (PENN 1 & PENN 2) | Trophy | Newly redeveloped Class A above Penn Station | Corporate HQs, finance, consulting, tech |
| Penn Plaza core (One, Five, 14 Penn Plaza) | Class A | Established Class A near the transit hub | Professional services, larger tenants |
| Garment District, Broadway & Seventh Ave spine | Mixed | Modernized Class A and Class B loft | Fashion, media, PR, showrooms |
| Garment District side streets (W 35th to 39th) | Value | Class B and Class C loft | Startups, small business, nonprofits |
| Western edge (Hudson Blvd / Manhattan West side) | Trophy | New Class A, Hudson Yards spillover | Tech, finance, large blocks |
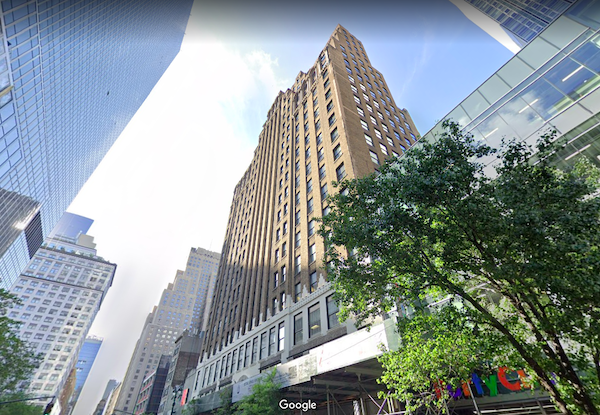
Five years ago, almost nobody put “Penn Station” and “trophy office” in the same sentence. The area was transit-rich and tired. Then Vornado bet the house on it, and the bet paid off. PENN 2, the 31-story, roughly 1.6 million SF tower sitting directly on top of the station, came out of a $750 million renovation with a new glass curtain wall, a triple-height lobby, 73,000 SF of outdoor space, and a brand-new Seventh Avenue entrance to Penn Station that Vornado calls the Bustle (Vornado Realty Trust, Q4 2025 earnings, February 2026). The space leased fast.
The numbers tell it plainly. Vornado leased 908,000 SF at PENN 2 in 2025 at an average starting rent of about $109/SF, with the tower floors closer to $114/SF, on leases averaging more than 17 years. The building went from 60% leased in mid-2025 to roughly 80% by the company’s Q4 2025 earnings call in February 2026, and Vornado said in June 2026 that it had reached 90% after full-floor leases with Veeva and Altana.
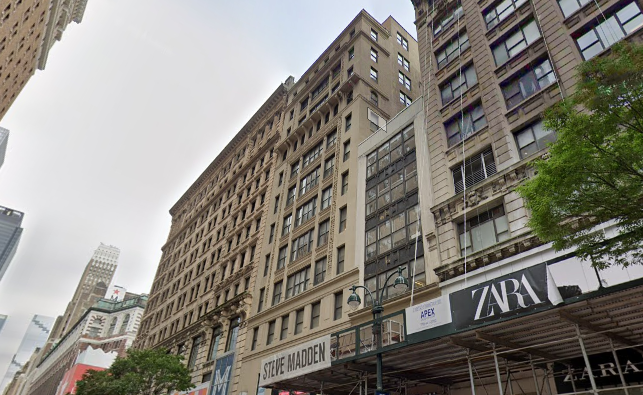
Across the street, the Garment District is playing a different game. Steve Madden signed a 13-year lease for 60,000 SF at Empire State Realty Trust’s 501 Seventh Avenue in 2026, moving its headquarters in from Long Island City at an asking rent in the low $60s/SF (Commercial Observer, April 30, 2026). A year earlier, Carolina Herrera renewed and expanded to 34,000 SF in the same building (Empire State Realty Trust, April 17, 2025).
It comes down to which half you pick. The Penn District trophy tier (PENN 1 and PENN 2) now prices above the Midtown Class A average of $90.57/SF (Cushman & Wakefield, Q3 2026), with PENN 2 floors leasing in the $109 to $125/SF range (Vornado, Q4 2025 earnings, February 2026; recent deal asks of $115 to $125/SF per The Real Deal and Commercial Observer, 2025 to 2026). The Garment District loft stock is a different animal: renovated Class A and B space generally runs $45 to $70/SF, and value loft on the side streets drops to $35 to $50/SF (Metro Manhattan internal research, June 2026). Midtown’s overall average was $78.83/SF in the third quarter, and Times Square South, which covers most of the Garment District, averaged $50.92/SF, the lowest in Midtown (Cushman & Wakefield, Q3 2026). So the Garment District is one of the few places you can land well under the district average and still walk to Penn Station.
Before you tour anything, get your size right. A fashion showroom, a 12-person startup, and a corporate HQ all shop this submarket, and they shop completely different buildings. Run your headcount through our Office Space Calculator first so you are touring the right tier instead of the whole zip code.
| Zone | Class A / Trophy Profile | Class B / C Coverage | Availability | Typical SF for New Leases | Tier |
|---|---|---|---|---|---|
| Penn District (PENN 1 & PENN 2) | Trophy, $109 to $125/SF | Minimal | Tight (PENN 2 90% leased, June 2026) | 20,000 to 200,000+ SF | Trophy |
| Penn Plaza core (One, Five, 14, 7 Penn) | Class A, mid-$60s to low-$80s/SF | Some Class B | Moderate | 3,000 to 50,000 SF | Class A |
| Garment District spine (Broadway / Seventh Ave) | Renovated loft, $50 to $70/SF | Strong Class B | Moderate | 2,500 to 60,000 SF | Mixed |
| Garment District side streets (W 35th to 39th) | Limited Class A | Class B and C dominate, $35 to $55/SF | Higher, but small spaces | 500 to 10,000 SF | Value |
| Western edge (Hudson Blvd / Manhattan West side) | New trophy, $100 to $150+/SF | None | Low | 20,000 to 100,000+ SF | Trophy |
Penn District trophy pricing reflects PENN 2 leasing (Vornado, Q4 2025 earnings, February 2026) and recent deal asks of $115 to $125/SF (The Real Deal and Commercial Observer, 2025 to 2026). All other zone-level rent ranges, Class B and C coverage descriptors, and availability characterizations are Metro Manhattan internal research (June 2026). PENN 2's 90% leased figure is from Vornado (June 2026). For comparison, Cushman & Wakefield puts its Penn Station submarket at $96.17/SF overall and $124.47/SF for Class A with 12.8% vacancy, and Times Square South at $50.92/SF with 21.3% vacancy; CBRE puts its Penn District/Hudson Yards district at $96.42/SF and 5.2% available; and Savills puts Penn Plaza/Times Square South at $62.23/SF (gross) and 11.7% available (all Q3 2026). No firm publishes zone-level figures at this granularity. Western edge reflects Hudson Yards-adjacent pricing where the submarket borders Manhattan West.
This is the part of the submarket that changed. PENN 2 is the headliner: roughly 1.6 million SF, 31 stories, $750 million renovation, sitting directly on the station (Vornado, February 2026). The tenant roster reads like a Class A building because it is one. Verizon signed for about 203,000 SF on a 19-year lease (Commercial Observer and CoStar, 2025) but never moved in, and Snap subleased those floors, about 199,000 SF, in August 2026 (Commercial Observer, August 3, 2026). Veeva and Altana each took a full floor of about 62,000 SF in June (Vornado, June 2026). Consulting giant Capgemini signed for 43,000 SF at an asking rent of $120/SF (Commercial Observer, 2025 to 2026). Communications firm FGS Global took 80,000 SF at $115/SF. Fintech firm Current took 62,000 SF at $125/SF, moving in from Chelsea. Add Dick’s Sporting Goods, Madison Square Garden, Major League Soccer, and Universal Music Group, and you have one of the more eclectic blue-chip tenant lists in Midtown.
If you need this kind of space, walk in knowing the leverage has shifted. These buildings are leasing well, transit is the selling point, and the landlord knows it. Lead with your credit and your term. For a deeper look at what actually separates a trophy building from ordinary Class A, see our piece on how trophy buildings set themselves apart in NYC.
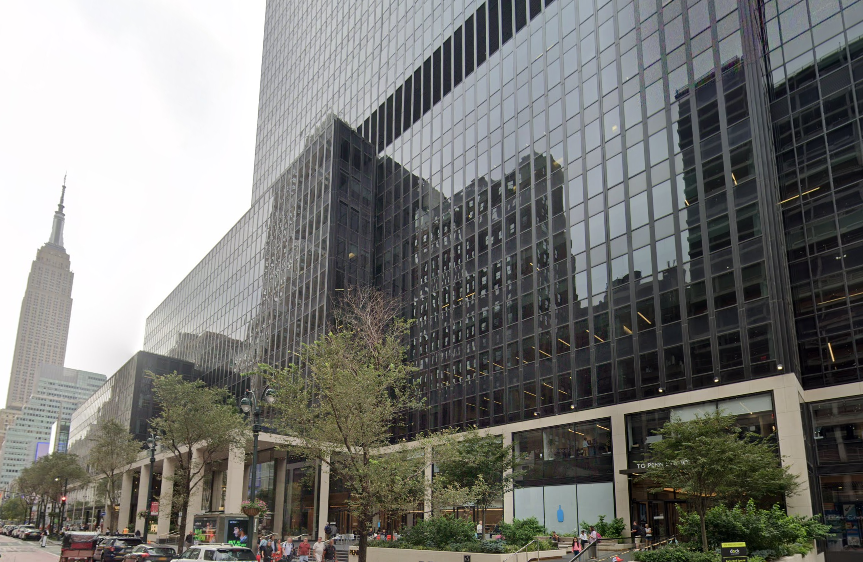
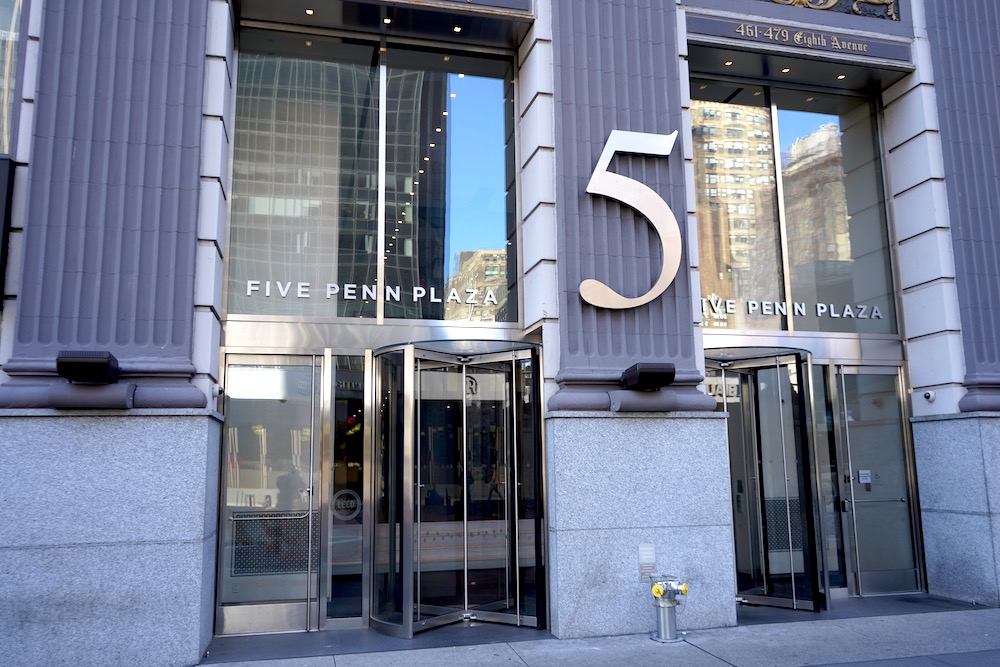
Not every Penn Station address is a brand-new trophy. The established Penn Plaza towers, One Penn Plaza at 230 West 34th Street, Five Penn Plaza, and 14 Penn Plaza at 225 West 34th Street, give you genuine Class A bones and the same transit access without the trophy price tag. These are large, efficient buildings that have housed names like Cisco and Citigroup. Pricing here generally runs in the mid-$60s to low-$80s/SF (Metro Manhattan internal research, June 2026), which suits a tenant who wants a real Penn Station address but doesn’t need the newest lobby in the neighborhood.
Now the other half. The Garment District is loft country: honest prewar Class B and C space, high ceilings, big windows, floor plates that divide well for smaller tenants. Some of the most flexible commercial loft space in Midtown, and fashion’s home turf for a century. The anchor buildings sit on the Broadway and Seventh Avenue spine: 1407 Broadway, 530 Seventh Avenue, and the Empire State Realty Trust portfolio at 501 Seventh Avenue, 1400 Broadway, and 1333 Broadway. ESRT has been modernizing these aggressively, adding rooftop lounges, town-hall conference space, and ground-floor retail, then re-signing fashion tenants into them.
On pricing, renovated Class A and Class B loft on the spine generally runs $50 to $70/SF, and Steve Madden’s low-$60s/SF asking at 501 Seventh confirms that band for a quality building (Commercial Observer, 2026). Head to the side streets between 35th and 39th and the Class B and C loft stock can drop into the $35 to $55/SF range (Metro Manhattan internal research, June 2026). One current example: a 1,300 SF suite at 221 West 37th Street with eleven-foot ceilings asking $37/SF. If you’re price-sensitive and you don’t need a marble lobby to land your next client, this is one of the best values in all of Midtown. Quick refresher on the building-class system here.
This is where most tenants lose money. They grind on the asking rent, win a couple of dollars, and sign, while most of the value is in free rent and the tenant improvement allowance. In the Penn District trophy tier, note that the big PENN 2 deals carried sizable free-rent packages baked in, which is part of why Vornado’s near-term cash flow dipped even as leasing boomed (Vornado, Q4 2025 earnings, February 2026). In the Garment District, concessions are even more tenant-friendly. The ranges below are typical-market figures from our recent deals (Metro Manhattan internal research, June 2026), assuming a 5 or 10-year term. Your actual numbers come down to credit, term, building, and how hard you push.
| Tier | Free Rent | TI Allowance | Notes |
|---|---|---|---|
| Penn District trophy (PENN 1, PENN 2) | 10 to 14 months free | $100 to $140/SF | Tighter than the loft stock, but the long terms here come with real build-out money. |
| Penn Plaza Class A | 12 to 16 months free | $80 to $110/SF | Strong value for a true Class A transit address. |
| Garment District renovated loft | 12 to 16 months free | $60 to $90/SF | Many ESRT and spine buildings now offer prebuilt, move-in-ready suites. |
| Garment District value loft | 10 to 16 months free | $40 to $70/SF | Plenty of landlords will hand you a built-out turnkey suite you can sign and occupy in 30 days. |
Typical-market figures from our recent deals (Metro Manhattan internal research, June 2026), assuming a 5 or 10-year term. Actual numbers depend on credit, term, building, and negotiation.
Two things worth reading before you sign anything in this submarket. First, the term length actually changes your whole package, so our breakdown of 3-year, 5-year, or 10-year lease terms is worth ten minutes. Second, free rent and TI are worth more than a few dollars off the rent, and our concessions explainer walks through it.
Tenants here sort themselves cleanly by industry and budget, and the dividing line is usually 34th Street and a price point. Fashion, media, and small business cluster in the Garment District loft stock. Corporate HQs, finance, and consulting head for the Penn District trophy towers. Match your industry and your size to the right zone, and the search gets a lot smaller. The table below shows the best fits.
| Industry | Best-Fit Zone | Class Fit | Example Buildings |
|---|---|---|---|
| Fashion / Apparel / Accessories | Garment District spine | Renovated loft / Class B | 501 Seventh Ave, 1407 Broadway, 530 Seventh Ave, 1400 Broadway |
| Media / Advertising / PR | Garment District spine, Penn District | Class B / Class A | 1407 Broadway, 1333 Broadway, PENN 2 |
| Corporate HQ / Large Occupiers | Penn District | Trophy | PENN 2 (Snap), One Penn Plaza |
| Consulting / Professional Services | Penn District | Trophy / Class A | PENN 2 (Capgemini, FGS Global), 5 Penn Plaza |
| Fintech / Financial Services | Penn District | Trophy / Class A | PENN 2 (Current), 14 Penn Plaza |
| Technology / SaaS | Penn District (larger), Garment side streets (smaller) | Trophy to Class C | PENN 2, The Spiral (edge), 255 West 36th |
| Showroom / Retail / Wholesale | Garment District (ground floor) | Class B | Seventh Avenue, including 530 and 515 Seventh Ave |
| Entertainment / Sports / Music | Penn District (MSG-adjacent) | Trophy | PENN 2 (MSG, MLS, Universal Music Group) |
| Startups / Small Business (<20 people) | Garment District side streets | Class B / Class C | 255 West 36th, 247 West 35th, 202 West 40th, 42 West 38th |
| Nonprofits / Back-office | Garment District side streets | Class B / Class C | Side-street loft stock, W 35th to 39th |
Metro Manhattan internal research (June 2026).
One more note for the small-business and startup crowd: the Garment District is one of the best landing spots in the city for a first real office, and it pairs naturally with flexible options nearby. If you are weighing a private space against a shared one, our guide to the top NYC neighborhoods for small businesses and our overview of coworking space are good starting points.
If your last tour here was pre-2020, the picture in your head is wrong, especially on the Penn side. The amenity bar in this submarket jumped, and it jumped at both ends. Three tiers to expect:
Penn District trophy tier (PENN 1, PENN 2): New curtain walls, triple-height lobbies, tenant amenity floors, conferencing, fitness, and serious outdoor space. PENN 2 alone has more than 73,000 SF of landscaped outdoor area, including a 17,000 SF roof, plus a 280-person town hall. Direct access to Penn Station and the Moynihan Train Hall. This is trophy-grade product on top of the busiest transit hub in the hemisphere.
Garment District modernized spine (501 Seventh Ave, 1400 Broadway, 1333 Broadway, 1407 Broadway): Renovated lobbies, rooftop lounges, shared town-hall conference space, and prebuilt suites. Empire State Realty Trust has built a connected campus across its Garment District buildings, with shared amenities and ground-floor retail. Real upgrades on a loft budget.
Garment District value loft (side streets, W 35th to 39th): Prewar character, high ceilings, big windows, freight access, and tenant-controlled HVAC. Light on frills, heavy on flexibility, and increasingly stocked with move-in-ready spec suites.
For a wider look at the best buildings in the borough, see our list of the top 10 Class A office buildings in Midtown. Or browse all buildings and filter active listings by size and price.
Two names own the story here, and they could not be more different. Vornado Realty Trust is the Penn District. It controls PENN 1, PENN 2, and the surrounding redevelopment, and it is playing for trophy rents and long corporate leases. Empire State Realty Trust is the Garment District spine, with a modernized campus of Broadway and Seventh Avenue buildings aimed at fashion, media, and smaller tenants. The rest of the loft stock is fragmented among private and family owners, which is good news if you like to negotiate. Background reading: the biggest commercial real estate landlords in NYC.
| Landlord | Notable Properties | Position in Submarket | Typical Lease Profile |
|---|---|---|---|
| Vornado Realty Trust | PENN 1, PENN 2, 7 Penn Plaza, 34th St / Seventh Ave retail | Dominant in the Penn District | 10,000+ SF, 15+ year |
| Empire State Realty Trust | 501 Seventh Ave, 1400 Broadway, 1333 Broadway, 1350 Broadway | Garment District spine "campus" | 2,000+ SF, small-tenant friendly |
| Tishman Speyer | The Spiral (66 Hudson Boulevard) | Western edge / Hudson Yards side | 10,000+ SF |
| Private & family-owned portfolios | Side-street loft stock, W 35th to 39th | Fragmented across the Garment District | 500 to 10,000 SF |
Landlord positioning is Metro Manhattan internal research (June 2026). Vornado is the dominant Penn District owner; Empire State Realty Trust holds the largest modernized Garment District portfolio; the bulk of the Garment District loft stock is held by smaller private and family ownership groups. Several of these landlords also operate significant inventory elsewhere in Midtown and beyond.
This is the submarket’s biggest strength, so lead with it when you’re selling the office to your team. You’re on top of Penn Station, the busiest passenger rail hub in the Western Hemisphere, with the renovated Moynihan Train Hall next door. That means Amtrak, the Long Island Rail Road, and NJ Transit all under your feet, plus a dense web of subway lines and the Port Authority Bus Terminal a few blocks north. Hudson Yards and the 7 train sit just to the west. If anyone on your team is resisting the commute, send them our Commute Calculator with their home address.
| From | To Penn Station / Garment District | Mode |
|---|---|---|
| Newark, NJ | 15 to 20 min | NJ Transit to Penn Station |
| Hoboken, NJ | 15 to 20 min | PATH to 33rd St + short walk |
| Jersey City (Exchange Place) | 18 to 25 min | PATH to 33rd St |
| Hicksville, NY (Long Island) | 40 to 50 min | LIRR to Penn Station |
| Stamford, CT | 55 to 70 min | Metro-North to Grand Central + 7 to Penn-area |
| Downtown Brooklyn | 20 to 30 min | 2, 3 to 34th St / Penn |
| Williamsburg, Brooklyn | 25 to 35 min | L to 6th Ave + 1, 2, 3 |
| Long Island City, Queens | 15 to 25 min | 7 to 34th St / Hudson Yards + short walk |
| Downtown Manhattan (Fulton) | 12 to 18 min | 2, 3 to 34th St / Penn |
It depends on which half of the submarket you mean. Cushman & Wakefield’s third-quarter 2026 report put asking rents in its Penn Station submarket, which runs from 30th to 36th Street at its widest, at $96.17/SF overall and $124.47/SF for Class A, against $78.83/SF for Midtown as a whole. Most of the Garment District falls in its Times Square South submarket, where the average was $50.92/SF. Full floors at PENN 2 were marketed at about $110 to $125/SF in 2026, while side-street loft suites we listed this year asked $33 to $39/SF.
Vornado spent about $750 million rebuilding PENN 2 directly above Penn Station, and tenants followed. The building leased 908,000 SF in 2025 at an average starting rent of about $109/SF, and Vornado said in June 2026 that it was 90% leased after full-floor deals with Veeva and Altana. Cushman & Wakefield’s third-quarter numbers put Class A asking rents in its Penn Station submarket at $124.47/SF, second in Midtown only to Park Avenue.
Yes, though it is smaller and more consolidated than it was decades ago. Fashion brands continue to sign and expand in the modernized buildings on Broadway and Seventh Avenue. Steve Madden took 60,000 SF for its headquarters at 501 Seventh Avenue in 2026, and Carolina Herrera expanded to 34,000 SF in the same building in 2025 (Commercial Observer, 2026; Empire State Realty Trust, 2025). Apparel and accessories remain the anchor industry, alongside media, advertising, and showroom tenants.
The Garment District side streets between 35th and 39th, west of Broadway, hold the most value, with Class B and Class C loft generally in the $35 to $55/SF range in our June 2026 read. Cushman & Wakefield’s third-quarter 2026 report put the average asking rent in Times Square South, the submarket that covers most of the Garment District, at $50.92/SF, the lowest in Midtown. These are smaller spaces, often 500 to 10,000 SF, which makes the area one of the better landing spots in Midtown for startups, small businesses, and nonprofits steps from Penn Station.
Side-street Garment District loft buildings such as 255 West 36th Street, 247 West 35th Street, 202 West 40th Street, and 42 West 38th Street offer flexible, smaller suites at competitive rents (Metro Manhattan internal research, June 2026). Many landlords here offer prebuilt, move-in-ready spec suites with short build-out timelines. For larger or better-funded startups, PENN 2 and the western edge near Hudson Yards offer trophy options.
Vornado announced in June 2026 that Veeva had leased the full 11th floor at PENN 2 (62,223 SF, 12 years) and Altana the full 21st (62,309 SF, 10 years), bringing the building to 90% leased. In August, Commercial Observer reported that Snap had subleased Verizon’s roughly 199,000 SF on the 8th through 10th floors through 2044, with Verizon consolidating into its existing New York offices. Earlier PENN 2 deals include FGS Global (80,000 SF), Current (about 62,000 SF), and Capgemini (43,000 SF), alongside Madison Square Garden, Major League Soccer, and Universal Music Group.
It splits by tier. Cushman & Wakefield’s third-quarter 2026 report put vacancy at 12.8% in its Penn Station submarket and 21.3% in Times Square South, the submarket that covers most of the Garment District, against 17.0% for Midtown as a whole. CBRE, which tracks only modernized buildings, put availability in its Penn District/Hudson Yards district at 5.2%, its lowest since 2000. Zone-level availability on this page is Metro Manhattan internal research (June 2026).
It’s the best argument the submarket has. Penn Station and the Moynihan Train Hall put Amtrak, the Long Island Rail Road, and NJ Transit directly underfoot, with the 1, 2, 3, A, C, and E subway lines on site and the B, D, F, M, N, Q, R, and W one block south at Herald Square. The Port Authority Bus Terminal and the 7 train to Hudson Yards are both a short walk away.
Vornado Realty Trust dominates the Penn District (PENN 1, PENN 2, 7 Penn Plaza), and Empire State Realty Trust holds the largest modernized Garment District portfolio (501 Seventh Avenue, 1400 Broadway, 1333 Broadway). Tishman Speyer owns The Spiral on the western edge, and the bulk of the Garment District loft stock is held by smaller private and family ownership groups (Metro Manhattan internal research, June 2026).
Most of the inventory in this submarket, especially the privately owned Garment District loft stock, never appears on public search platforms. A broker provides access to those spaces and knows which buildings offer the strongest concessions and prebuilt suites. Brokerage commissions are paid by the landlord, so the cost to the tenant is zero.
Accessibility Tools