
Upgrade From Class C to Class A: The Power of High-End Office Furniture
Suppose your office space is functional yet drab, uninspiring, and a canvas of untapped potential.


Flatiron is where the AI money is going. It’s not the only place, but it’s the busiest one. For two years now the fastest-growing software and AI companies in New York have been signing leases between Union Square and Madison Square Park, and this year that went from a trend to the main thing driving the market. Savills says Midtown South availability fell 470 basis points to 14.4% as tech and AI companies kept absorbing space, and a lot of that demand is landing right here in Flatiron and along Park Avenue South (Savills, Q3 2026).
But the headlines leave something out: Flatiron is really two markets. Up on Park Avenue South and around Madison Square Park, AI and fintech tenants are signing from $90 to $120/SF and buildings are hitting 100% leased. Three blocks west, on the Sixth Avenue side and the prewar side streets, there’s still real loft space at real prices for a growing company that doesn’t need to make a statement. Where you land in these dozen blocks matters far more than the fact that you landed in Flatiron, the highest-profile submarket in Midtown South.
Many of our clients are teams of 5 to 30 people. The Flatiron headlines this year were AI companies taking big blocks of space: Clay took 163,000 SF at 11 Madison Avenue, and Synthesia moved its headquarters into about 50,000 SF at 675 Avenue of the Americas (Commercial Observer, 2026). Most buildings here are far smaller, and plenty of them lease suites of 1,100 to 5,500 SF.
Plan on about 150 to 250 square feet per person, depending on how many private offices you want. That works out to roughly 750 to 1,250 square feet for 5 people, 2,250 to 3,750 for 15, and 4,500 to 7,500 for 30. Our office space calculator will give you a closer number before you tour.
The side streets between Fifth and Sixth Avenues are where small teams get the most for their money. Suites on our site in October at 19 West 21st, 37 West 20th, and 54 West 21st Streets asked $33 to $56/SF, and 928 Broadway asked $50 to $58/SF. At $55/SF, a 2,000 SF office for about ten people costs about $9,200 a month before electricity. Renovated buildings that AI tenants want have asked $75 to $85/SF this year, including 156 Fifth Avenue and 43 West 23rd Street (Commercial Observer, 2026).
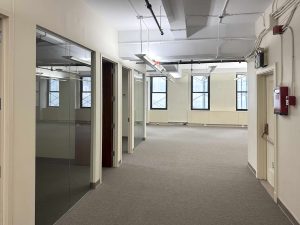
Ask about prebuilt suites. The landlord builds them out before you sign, with private offices, a conference room, and a kitchen, so you can move in within weeks instead of waiting months for construction. When Taconic renovated 61 West 23rd Street, it added prebuilt offices (Commercial Observer, September 2026).
Buildings to start with:
One deal of ours: in 2023, we moved DFW Capital Partners, a private equity firm relocating from New Jersey, into a 3,000 SF corner suite at 156 Fifth Avenue on a five-year lease. The space came as a white box, and the firm built six offices and a large conference room.
For two to five people, a private office in a coworking space can cost less than a lease of your own.
| Sub-Area | Profile | Best For | Tier |
|---|---|---|---|
| Park Avenue South | The AI and tech spine running up the east edge of the district | AI, fintech, SaaS, venture capital | Premium |
| Madison Square & NoMad edge | Full-block trophy and renovated towers fronting Madison Square Park | AI flagships, finance, professional services | Trophy / Premium |
| Fifth Avenue & Broadway (Flatiron core) | Famous loft and tower buildings in the center of the district | Tech, media, creative, showroom | Class A loft |
| Sixth Avenue / Ladies’ Mile | Converted cast-iron department stores on the west side | Tech, retail, showroom, fashion | Class A / B loft |
| Flatiron side streets | Prewar loft side-street inventory between Fifth and Sixth | Startups, small business, medical, nonprofits | Value to mid-market |
Tenants who treat Flatiron as one market waste a lot of time. It’s an AI trophy cluster and a value loft district on the same few blocks, and a deal at One Madison Avenue has nothing in common with a deal in a prewar loft off Sixth. Figure out which one you’re shopping before you tour anything, or you’ll lose a month on buildings that were never going to work.
The backdrop is loud. CBRE counts 6.22 million SF of Midtown South leasing through September, the highest year-to-date total on record, and puts district availability at 16.2% (CBRE, Q3 2026). Flatiron is far tighter. CBRE has its Flatiron district at 7.4% available, down a full point in the quarter, and Savills has Flatiron at 7.5%, the second-tightest Manhattan submarket it tracks after Hudson Yards (Savills, Q3 2026). With that little space left, it’s no surprise CBRE says Flatiron’s third-quarter leasing ran behind its usual pace.
Want the proof? Look at who’s signing.
When companies growing this fast commit to ten-year leases at the top of the market, you stop arguing with the chart. For the wider pattern, see our breakdown of the largest Manhattan office leases behind the numbers.
The answer depends on which side of the neighborhood you pick. CBRE’s third-quarter numbers put the Midtown South average at a record $86.94/SF and its Flatiron district at $74.24/SF. On a 3,000 SF office, that $12.70 gap is worth about $38,000 a year, and even the Flatiron average is close to useless on its own, because the spread inside these blocks is enormous. One Madison Avenue asked around $120/SF before it filled. 11 Madison asked $90/SF on Clay’s lease in March. Hex, an AI company out of San Francisco, took a full floor at 250 Park Avenue South at $80/SF (Commercial Observer, January 2026). And on the prewar side streets off Sixth, you can still find office space in the $60s.
So before you tour, answer one question: do you need to be on the AI blocks, or do you just need to be in Flatiron? If you’re a venture-backed AI company competing with OpenAI for talent, you’ll probably pay up for Park Avenue South and Madison Square. If you’re a profitable services firm or a growing startup that wants the neighborhood and the commute without the trophy bill, look west and on the side streets. It’s the same neighborhood and the same trains, at very different rent. Not sure how much space you need? Run your headcount through our Office Space Calculator before you tour anything.
If you haven’t shopped Midtown South before, know this up front: the Class A, B, C system doesn’t work here the way it does in Midtown or Downtown. Most of Flatiron’s buildings are converted lofts, former warehouses, and turn-of-the-century cast-iron, not purpose-built office towers. So a 1900s loft on Park Avenue South can technically carry a Class B label and still command rent that beats a Class A tower uptown, because the ceiling height, the light, the floor plate, and the address are what tenants actually pay for. Class describes the building. Rent tier describes what tenants pay. Don’t get hung up on the letter. Our explainer on what makes a building Class A, B, or C breaks it down.
| Sub-Area | Class A Profile | Class B / C Coverage | Availability | Typical SF for New Leases | Tier |
|---|---|---|---|---|---|
| Park Avenue South | Renovated loft and prewar tower (AI cluster) | Limited Class B | ~10 to 14% | 5,000 to 100,000+ SF | Premium |
| Madison Square & NoMad edge | Trophy and Class A (11 / One Madison) | Minimal Class B | ~5 to 12% | 10,000 to 100,000+ SF | Trophy / Premium |
| Fifth Avenue & Broadway (core) | Class A loft | Class B available | ~12 to 15% | 2,500 to 40,000 SF | Class A loft |
| Sixth Avenue / Ladies' Mile | Class A / B loft | Class B and C available | ~13 to 16% | 2,000 to 50,000+ SF | Class A / B loft |
| Flatiron side streets | Limited Class A | Class B and C dominate | ~14 to 17% | 1,500 to 15,000 SF | Value |
| Flatiron average (CBRE, Q3 2026) | $74.24/SF overall; no Class A figure | Not separately published | 7.4% (Savills: 7.5%) | Varies | Mixed |
Flatiron district average asking rent of $74.24/SF and availability of 7.4% from CBRE, Manhattan Midtown South Office Figures Q3 2026 (October 7, 2026), against $86.94/SF and 16.2% for Midtown South overall. Savills, which tracks Flatiron and Park Avenue South as separate submarkets, has Flatiron at $67.81/SF with 7.5% availability and Park Avenue South at $72.56/SF with 13.2% (gross asking, Q3 2026). Sub-area profiles, coverage descriptors, and availability ranges are Metro Manhattan internal research (September 30, 2026); approved firms publish Midtown South, and in some cases Flatiron or Park Avenue South, figures, but do not publish breakouts by sub-area at the level shown here. Building-specific asking rents (11 Madison $90/SF, One Madison about $120/SF, 250 Park Avenue South $80/SF) are marketed quotes, not submarket averages.
Park Avenue South is where the change shows most. For a decade it was a solid but unremarkable stretch of lofts. Then the AI companies arrived, and rents reset. The biggest deals of 2025 and 2026 all landed within a few blocks of Madison Square Park. Clay took 163,000 SF at 11 Madison Avenue at $90/SF (Commercial Observer, March 9, 2026), Harvey AI expanded to roughly 185,000 SF at One Madison Avenue, where asking rents ran around $120/SF, and Pinterest and Tempus AI took space at 11 Madison. Smaller AI tenants keep coming too, like Hex at 250 Park Avenue South (Commercial Observer, January 2026). The two anchors, 11 Madison and One Madison, are both owned by SL Green and both fully leased: One Madison since March and 11 Madison since July, when Legora took 98,420 SF (SL Green, 2026).
These are full-block trophy and trophy-adjacent buildings with the amenity packages and the addresses AI flagships want. If you need that kind of space, timing matters more than budget, because these buildings fill faster than they empty. For what actually separates trophy from regular Class A, see our piece on how trophy buildings set themselves apart in NYC. One caveat on geography: 11 Madison and One Madison sit on the Madison Square edge, which the site’s taxonomy also covers under Park Avenue / Madison Square. Different page, same cluster.
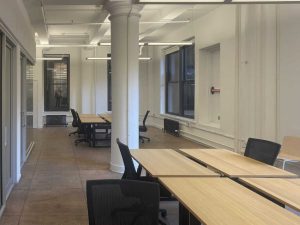
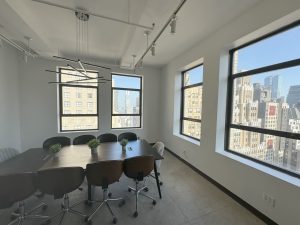
Step away from the AI blocks and Flatiron is mostly lofts: renovated prewar and cast-iron buildings with high ceilings, big windows, and floor plates that suit a 5,000 to 40,000 SF tenant. This is where most Flatiron leases that aren’t AI megadeals get signed, and there’s a lot to choose from. Many of these landlords have spent heavily on lobbies and prebuilt suites in the last five years, so a renovated loft here often shows better than a glass tower from 2008. The character is the point, and tenants pay for it. The best of this stock spans Fifth Avenue, Broadway, and the blocks around the old Flatiron Building.
One thing to know: the Flatiron Building itself, at 175 Fifth Avenue, is no longer an option. After 120 years as offices, it’s being converted to 38 luxury condominiums, scheduled to finish by year-end (6sqft, 2026). The ground floor will keep retail, including a new restaurant from the team behind Bar Pisellino, but the office floors are gone. If you want the most famous triangular silhouette in America, you’ll have to buy a condo.
The value is on the west side, and a lot of tenants miss it. On the Sixth Avenue side, in the converted Ladies’ Mile department stores, and on the prewar side streets between Fifth and Sixth, Flatiron still has loft space that rents well below Park Avenue South. The submarket averages are closer than you’d think: Savills had Flatiron at $67.81/SF in the third quarter against $72.56/SF for Park Avenue South, and CBRE has both of its districts at about $74 (Q3 2026). Averages blend every building together, though, and the savings show up building by building. You get the same neighborhood and the same trains for noticeably lower rent. This tier works for startups, small and midsize firms, medical and dental practices, nonprofits, and anyone who wants to be in Flatiron without paying AI-cluster rents.
Side-street buildings off Sixth in the West 18th to 22nd Street range carry strong 1,500 to 15,000 SF inventory, and a fair amount of it comes as spec suites you can move into fast. A chunk also trades as sublease, which can be the quickest, cheapest way in if the term fits. Two practical notes before you sign. First, the big brokerages don’t publish a separate Class C average for Flatiron, so anyone who quotes you a single Class C number is guessing. Our value-tier read comes from Metro Manhattan internal research (September 30, 2026). Second, almost every NYC landlord will want a security deposit, and for smaller or newer companies, a Good Guy Guarantee, so understand both before you negotiate. If you’re coming out of a coworking space, our guide to scaling from coworking to your own office walks through it.
Most tenants lose money in the same place. They negotiate the asking rent, win a few dollars, and sign without pushing hard on free rent or the build-out allowance, which is where most of the value is in a Flatiron loft deal. Who pays for the build-out is negotiable, and away from the AI blocks you have more room than you think. The ranges below are typical-market figures from our recent deals (Metro Manhattan internal research, September 30, 2026), assuming a 5 or 10-year term. Shorter terms get smaller packages, and 10- to 15-year terms get bigger ones. CBRE puts the Midtown South average for new raw-space leases at 17 months free and $160.17/SF in build-out money (CBRE, Q3 2026), but that average is driven by large, long-term deals. Small suites get far less, and free rent rarely goes past 12 months. On a 2,500 SF office at Flatiron’s average of about $74/SF, every free month is worth about $15,400.
| Tier | Free Rent | Tenant Improvement Allowance | Notes |
|---|---|---|---|
| Park Avenue South and trophy | 8 to 12 months free | TI $100 to $160/SF | The tightest concessions in Flatiron, because there's often an AI tenant lined up behind you. |
| Standard Class A loft | 8 to 12 months free | TI $80 to $120/SF | The best balance of a real Flatiron address and real concessions. |
| Class B loft | 6 to 12 months free | TI $60 to $90/SF | Spec suites widely available. Take a 10-year term and this tier still has serious leverage. |
| Class C and value | 6 to 12 months free | TI $40 to $70/SF | Many landlords will hand you a turnkey, fully built-out suite. Sign one month, move in the next. |
Typical-market figures from our recent deals (Metro Manhattan internal research, September 30, 2026), assuming a 5 or 10-year term. Shorter terms get smaller packages, and 10- to 15-year terms get bigger ones. Free rent rarely goes past 12 months, even on a 10-year term. CBRE’s Midtown South average of 17 months free (Q3 2026) is driven by large, long-term deals.
One more thing: net effective rent usually comes in well below the face rent a landlord first quotes, and knowing how to work it out can turn a fine deal into a great one. Our breakdown of 3-year, 5-year, or 10-year lease terms covers how term length moves the package, and our concessions explainer walks through the effective-rent math.
Flatiron tenants cluster tightly by industry, and not by accident. AI and fintech want Park Avenue South and Madison Square. Media, creative, and showroom tenants want the lofts off Fifth and Sixth. Smaller firms want the prewar side streets. There’s a reason: your clients, your talent, and the company down the block you want to poach from are already there. Match your industry to the right sub-area, and the search gets a lot smaller. The table below shows the best fits.
| Industry | Best-Fit Sub-Areas | Inventory / Class | Rent Tier | Example Buildings |
|---|---|---|---|---|
| AI / Machine Learning | Madison Square edge, Park Avenue South | Trophy and renovated loft | Premium | 11 Madison Ave (Clay, Tempus), One Madison (Harvey AI), 250 Park Ave South (Hex) |
| Fintech / Trading | Park Avenue South, Sixth Ave / Ladies' Mile | Renovated loft and cast-iron | Premium | 28-40 West 23rd (Ramp), 225 Park Ave South |
| Technology / SaaS | Park Avenue South, Fifth Ave & Broadway, Sixth Ave | Renovated loft | Mid to Premium | 122 Fifth Ave (Microsoft), 902 Broadway, 225 Park Ave South, 200 Fifth Ave |
| Media / Publishing / Creative | Fifth Ave & Broadway, Sixth Ave / Ladies' Mile | Cast-iron and renovated loft | Mid-market | 200 Fifth Ave, 915 Broadway, 1115 Broadway |
| Venture Capital / Investment | Madison Square edge, Fifth Ave & Broadway | Boutique and trophy loft | Premium | One Madison, 11 Madison |
| Professional Services (Legal, Accounting, Real Estate) | Park Avenue South, Madison Square edge | Renovated loft and prewar tower | Mid to Premium | 381 Park Ave South (Corcoran), 387 Park Ave South, 225 Park Ave South |
| Healthcare / Medical Practices | Fifth Ave & Broadway, Flatiron side streets | Prewar loft and converted office | Mid-market | 71 West 23rd, 902 Broadway, 30 East 20th, 215 Park Ave South |
| Fashion / Apparel / Showroom | Sixth Ave / Ladies' Mile, Fifth Avenue | Cast-iron loft (showroom-ready) | Variable | 28-40 West 23rd, Ladies' Mile cast-iron, Fifth Avenue showroom floors |
| Startups / Small Business (under 20 people) | Flatiron side streets, Sixth Ave / Ladies' Mile | Prewar loft side-street inventory | Value to Mid | 19 West 21st, 37 West 20th, 54 West 21st, 1133 Broadway, 113-133 West 18th |
| Retail / Storefront | Fifth Avenue, Broadway, Sixth Ave | Ground-floor retail | Variable | Flatiron core retail, Ladies' Mile flagships |
Vertical landing pages: Startup & Tech Space, Financial Services, Law Firm Offices, Medical Offices. Sub-area and class fits are Metro Manhattan internal research (September 30, 2026).
Running a lean team? Flatiron isn’t the cheapest corner of Manhattan, and the deepest value is elsewhere. But the side streets off Sixth make sense once you factor in the talent you can recruit by being in the AI neighborhood. Our guide to the top neighborhoods for small businesses lays out the trade-offs. If you want to be near the AI cluster but can’t afford Park Avenue South, AI companies are also leasing in SoHo, Chelsea (where Clay leased before its move to 11 Madison), and even down to the Financial District. Scale AI recently moved there to fit a workforce that doubled to 500 (The Real Deal, 2026).
If your last Flatiron tour was pre-2020, the picture in your head is wrong. The AI money pulled the amenity game up to Midtown trophy standards, and the best buildings here now compete on lounges and terraces, not just exposed brick. Three tiers to expect:
Trophy and Class A core (11 Madison, One Madison): Tenant-only amenity floors, conferencing, lounges, fitness, rooftop event space, and Madison Square Park views. Marquee on-site dining, with three-Michelin-star Eleven Madison Park at 11 Madison and La Tete d’Or by Daniel Boulud at One Madison. Smart-building systems. It’s the top of Midtown South.
Renovated loft (28-40 West 23rd, 225 Park Avenue South, 122 Fifth Avenue, 200 Fifth Avenue): Restored lobbies, new mechanical systems, on-site fitness and conferencing in the bigger buildings, ground-floor retail, and the high ceilings and natural light that draw tenants to lofts in the first place.
Class B and value loft (71 West 23rd, 113-133 West 18th, side-street prewar stock): Prewar character, big windows, attended lobbies, tenant-controlled HVAC, and a growing number of fully built-out spec suites with furniture and cabling already in place so you can move in fast.
Ground-floor and flagship retail space along Fifth Avenue, Broadway, and the Ladies’ Mile stretch of Sixth is some of the highest-traffic retail in the neighborhood. If you’re after a storefront rather than a floor upstairs, that’s a different search, and a very good one here.
Who owns your building matters as much as which building you pick, because every major Flatiron landlord negotiates differently. SL Green, the city’s largest office landlord, owns both Madison Square anchors, filled both of them this year, and posted its best first quarter in 28 years, so it’s dealing from strength and pushing hard (SL Green, March and July 2026). Williams Equities holds the Ramp building and runs a tight, well-capitalized shop. Smaller owners like Olmstead, Feil, and Bromley are aggressive on the Park Avenue South side and will move quickly for the right tenant. A good broker knows what you’re walking into. For background, see our overview of the biggest commercial real estate landlords in NYC. Several of these owners also hold much larger portfolios in Downtown Manhattan, where the same dollar buys more space.
| Landlord | Notable Flatiron Properties | Approx. Portfolio | Typical Lease Profile |
|---|---|---|---|
| SL Green Realty | 11 Madison Avenue (with PGIM), One Madison Avenue | ~25M SF (NYC's largest office landlord) | 10,000+ SF, 10+ yr |
| Williams Equities | 28-40 West 23rd Street (Ramp anchor) | ~1M SF Midtown South | 5,000+ SF |
| The Feil Organization | 250 Park Avenue South | Diversified national owner | 5,000+ SF |
| Olmstead Properties / Vertex (JV) | 381 Park Avenue South, Flatiron holdings | Active Flatiron acquirer | 2,500+ SF |
| TF Cornerstone | 387 Park Avenue South | Mixed-use developer | 5,000+ SF |
| The Bromley Companies | 122 Fifth Avenue | Single-asset focus in Flatiron | 10,000+ SF |
| PGIM Real Estate (Prudential) | 11 Madison Avenue (40% stake, with SL Green) | Institutional investor | Owner / JV |
| Rockrose Development | 11 East 26th Street, Madison Square holdings | ~2M SF Midtown South | 5,000+ SF |
Portfolio figures are approximate and weighted toward Flatiron and the broader Midtown South market. Several owners listed (SL Green, PGIM) hold substantially larger portfolios across Midtown, Midtown South, and Downtown. Metro Manhattan internal research (September 30, 2026).
Flatiron sits right in the center of Manhattan, which makes it a faster commute from almost everywhere than your team probably realizes. Union Square anchors the south end with eight subway lines, the 23rd Street stations cover the core, PATH runs to New Jersey, and Penn Station and Grand Central are both a short hop away. If anyone on your team is resisting the commute, send them our Commute Calculator with their home address. The numbers usually make the case.
| From | To Flatiron (23rd St / Union Square) | Mode |
|---|---|---|
| Hoboken, NJ | 10 to 15 min | PATH to 14th or 23rd St |
| Jersey City (Exchange Place) | 12 to 18 min | PATH to 14th or 23rd St |
| Newark, NJ | 25 to 30 min | NJ Transit to Penn + 1 stop |
| Williamsburg, Brooklyn | 10 to 15 min | L to Union Square |
| Bushwick, Brooklyn | 20 to 28 min | L to Union Square |
| Downtown Brooklyn | 15 to 22 min | 4, 5 or R to Union Square / 23rd St |
| Park Slope, Brooklyn | 20 to 28 min | R to 23rd St |
| Long Island City, Queens | 15 to 22 min | 7 to Times Sq + transfer |
| Astoria, Queens | 25 to 35 min | N or W to Union Square / 28th St |
| Hicksville, NY (Long Island) | 45 to 55 min | LIRR to Penn + 1 to 2 stops |
| Stamford, CT | 55 to 65 min | Metro-North to Grand Central + 4, 5, 6 |
It depends heavily on which side of the neighborhood you’re on. CBRE’s third-quarter numbers put the average asking rent in its Flatiron district at $74.24/SF, against $86.94/SF for Midtown South overall. Around Madison Square Park, 11 Madison Avenue asked $90/SF on Clay’s lease in March (Commercial Observer, March 2026). On the side streets off Sixth, small suites on our site in October asked about $33 to $56/SF.
Only one part of it repriced. AI and fintech companies made Park Avenue South and Madison Square Park the center of New York’s AI office market, and CBRE says AI firms signed 58% of all Midtown South leasing in the third quarter. Deals like Clay’s lease at 11 Madison, which asked $90/SF, and Harvey’s expansion at One Madison pulled the top of the market up (Commercial Observer; SL Green, 2026). Three blocks west, prices have moved far less.
The value runs along the Sixth Avenue side, through the converted Ladies’ Mile buildings, and on the prewar side streets between Fifth and Sixth (Metro Manhattan internal research, September 30, 2026). Savills’ third-quarter numbers put Flatiron’s average asking rent at $67.81/SF against $72.56/SF for Park Avenue South, though Flatiron’s 7.5% availability means fewer spaces to choose from. Side-street buildings in the West 18th to 22nd Street range carry strong 1,500 to 15,000 SF inventory.
Park Avenue South and the full-block towers fronting Madison Square Park, led by 11 Madison Avenue and One Madison Avenue (Metro Manhattan internal research, September 30, 2026). One Madison has been fully leased since March 2026, and 11 Madison filled in July, when Legora signed for 98,420 SF (SL Green; CBRE, third quarter 2026). Asking rents ran $90/SF on Clay’s lease at 11 Madison and have been reported at about $120 to $180/SF at One Madison (Commercial Observer; New York Post).
CBRE’s third-quarter numbers put availability in its Flatiron district at 7.4%, down a full point from the second quarter and well below 16.2% for Midtown South. Savills had Flatiron at 7.5%, the second-tightest submarket it tracks in Manhattan after Hudson Yards. Availability splits sharply by area: near-full on the AI side around Madison Square, looser in older loft stock on the side streets and the Sixth Avenue edge.
Ramp expanded to 285,300 SF at 28-40 West 23rd Street in the first quarter, and Clay signed for 163,095 SF at 11 Madison Avenue in March (The Real Deal; Commercial Observer, 2026). In July, Legora took 98,420 SF at 11 Madison, filling the building (CBRE), and in October, Synthesia moved its headquarters into about 50,000 SF at 675 Avenue of the Americas (Commercial Observer). Smaller AI firms signed at 43 West 23rd Street in July and at 61 West 23rd Street in September (Commercial Observer).
In Flatiron the class system is less useful than in Midtown or Downtown, because most buildings are converted lofts and turn-of-the-century cast-iron rather than purpose-built towers. A renovated 1900s loft can carry a Class B label and still out-rent a Class A tower uptown, because tenants pay for ceiling height, light, floor plate, and address. Our explainer on what makes a building Class A, B, or C breaks down the distinctions.
No. After more than a century as commercial offices, the Flatiron Building at 175 Fifth Avenue is being converted into 38 luxury condominiums by the Brodsky Organization, GFP Real Estate, and Sorgente Group, with the conversion scheduled to finish by year-end (6sqft, 2026). The ground floor will retain retail, but the upper floors are residential. Tenants who want the Flatiron address now look to the surrounding loft and tower stock instead.
Talent, peers, and product. The neighborhood already had a dense tech and startup base, the loft floor plates suit fast-growing engineering teams, and clustering near other AI firms helps with recruiting and visibility. Cushman & Wakefield’s third-quarter numbers count 2.8 million SF of AI-related leasing in Manhattan this year through September, nearly triple the 2025 total and more than any full year before it. As Park Avenue South tightens, the cluster is spilling into SoHo, Chelsea, and the Financial District.
Flatiron sits at the center of Manhattan’s transit grid. Union Square (4, 5, 6, L, N, Q, R, W) anchors the south end, the 23rd Street stations (1, F, M, N, R, W, 6) cover the core, and PATH reaches New Jersey from 14th, 23rd, and 33rd Streets. Penn Station and Grand Central are both a short ride away, putting the LIRR, Metro-North, NJ Transit, and Amtrak within reach.
A lot of Flatiron inventory, especially the best loft floors and spec suites, never reaches public search platforms, and a broker provides access plus knowledge of which landlords are dealing and where asking rents have room to move. Brokerage commissions are paid by the landlord, so the cost to the tenant is effectively zero. Before you tour, it’s worth reviewing the essentials to ask before leasing NYC office space.
Accessibility Tools